

Auto Insurance San Jose California
Auto Insurance San Jose, California
Auto insurance for San Jose drivers, quoted across several carriers by Rais Insurance.
Driving anywhere in Santa Clara County means carrying cover you can rely on when something goes wrong – and you rarely get notice. The auto insurance San Jose drivers need is worth arranging before an incident rather than after, whether the fault turns out to be yours or somebody else’s.
One correction on the original version of this page before anything else, because it shapes everything that follows: no policy covers “any and all incidents”. Knowing where yours stops is more useful than believing it does not.
What a Policy Does Not Cover
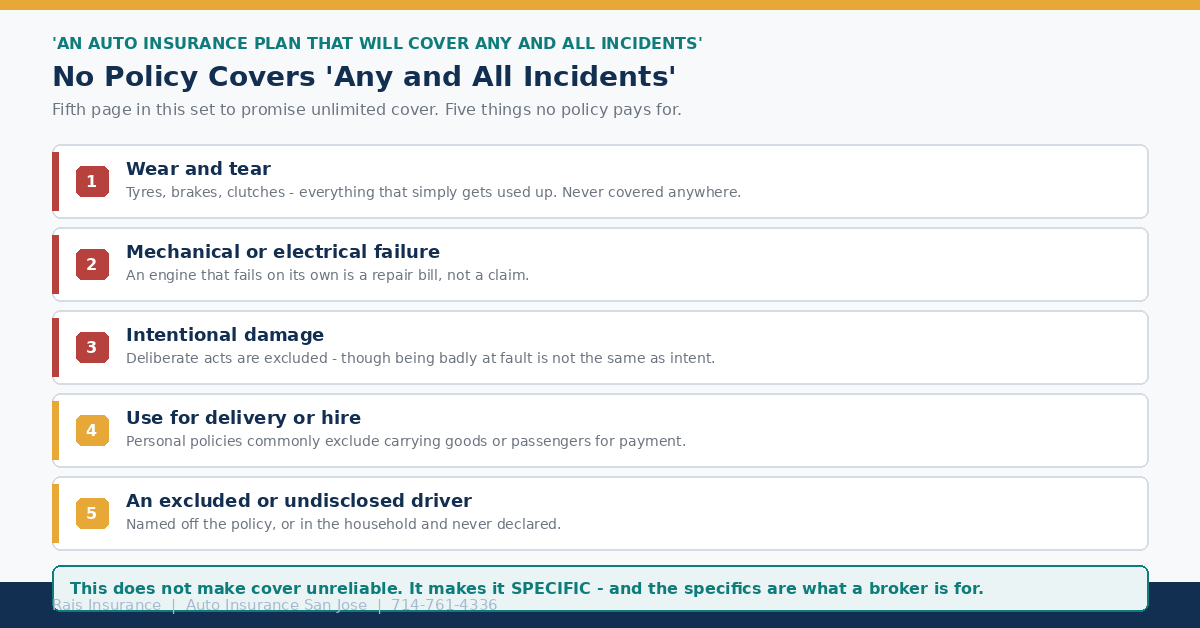
The fifth page in this set to promise unlimited cover.
Every car insurance policy is a defined set of coverages, each with a limit and most with a deductible. Five things no policy pays for:
- Wear and tear.Tyres, brakes, clutches and everything else that simply gets used up. Never covered, on any policy anywhere.
- Mechanical or electrical failure.An engine or gearbox that fails on its own is a repair bill, not a claim: see what a policy will not pay for.
- Intentional damage.Deliberate acts are excluded, though being badly at fault is not the same thing as intent.
- Use for delivery or hire.Personal policies commonly exclude carrying goods or passengers for payment – see conduct and use exclusions.
- An excluded or undisclosed driver.If somebody was named off the policy, or lives in the household and was never declared, a claim involving them can fail.
None of that makes cover unreliable. It makes it specific – and the specifics are what a broker is for.
The Three Named, and the Three Missing
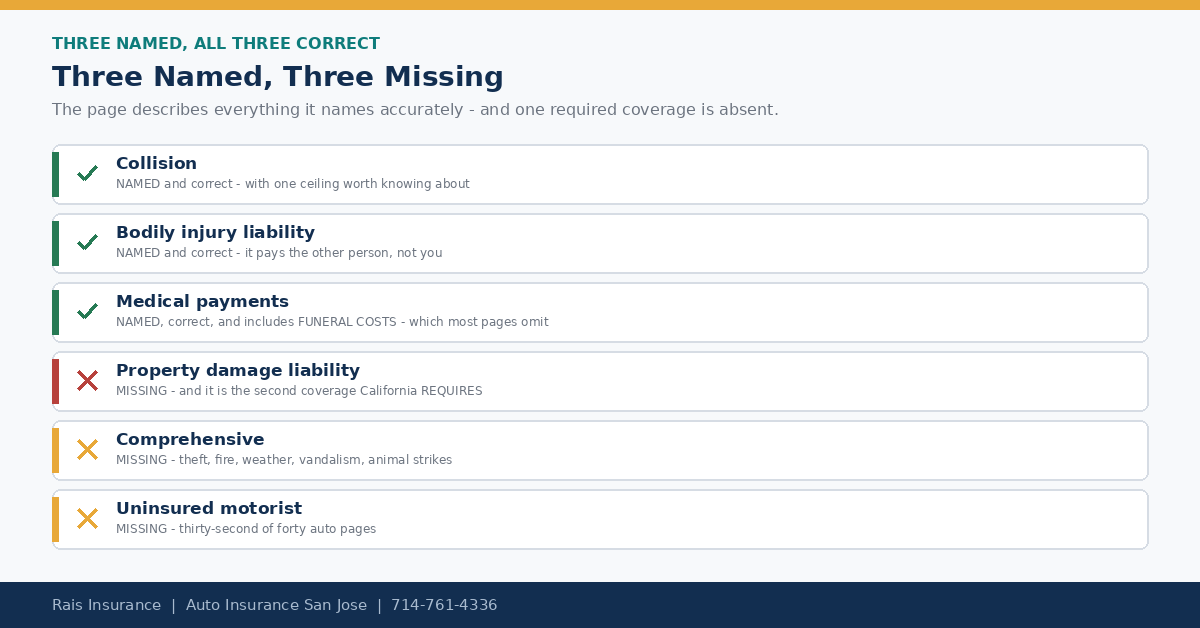
All three named are described correctly – and one required coverage is absent.
The original names three coverages and describes all three correctly, which is better than most pages in this position manage:
- Collision– damage to your own vehicle in an accident. Correct, with one important qualification below.
- Bodily injury liability– injuries you cause to other people, and their medical expenses. Correct, including that it pays for the other person rather than for you.
- Medical payments– your own medical costs after an accident, and, as the original says, funeral expenses in the worst case. Correctly named and correctly described; most pages call it “medical coverage” and omit the death benefit entirely.
Three more car insurance coverages belong on the list, and one of them is not optional:
- Property damage liability – required.California requires this alongside bodily injury liability. It pays for damage you cause to other people’s vehicles and property, and a policy without it does not meet the state minimum.
- Comprehensive – optional.Theft, fire, weather, vandalism, falling objects and animal strikes: see what comprehensive coverage actually covers.
- Uninsured and underinsured motorist – optional, declined in writing, and the only thing that responds when the driver who hits you has no insurance. Collision does not substitute for it: collision repairs your car, and says nothing about your injuries or losses.
The full list and the current minimum limits are on our auto insurance in California page.
What collision actually pays
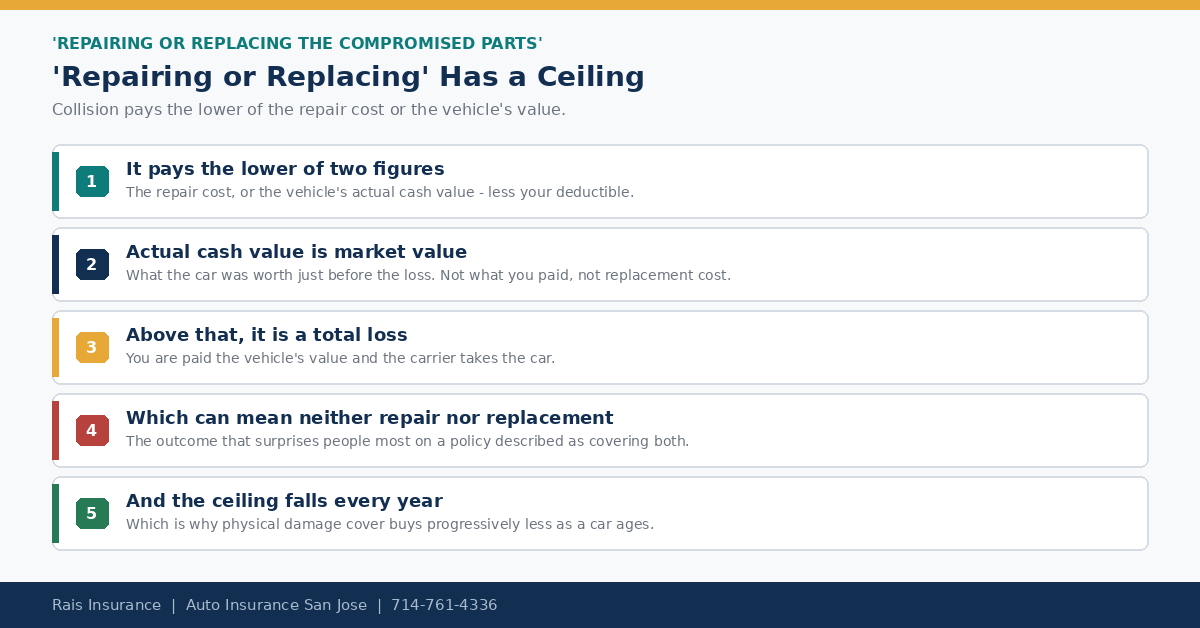
Collision pays the lower of repair cost or the vehicle’s value.
The original says collision pays “the expenses related to repairing or replacing the compromised parts”. True as far as it goes, and there is a ceiling worth knowing about:
- It pays the lower of two figures– the repair cost, or the vehicle’s actual cash value – less your deductible.
- Actual cash value is what the car was worth immediately before the loss.Its market value, not what you paid and not what a replacement costs today.
- If repairs would cost more than the car is worth, it is declared a total loss. You are paid its value and the carrier takes the vehicle.
- That ceiling falls every year, which is why physical damage cover buys progressively less as a car ages: see when collision and comprehensive stop earning their premium.
Why There Is No Standard Package
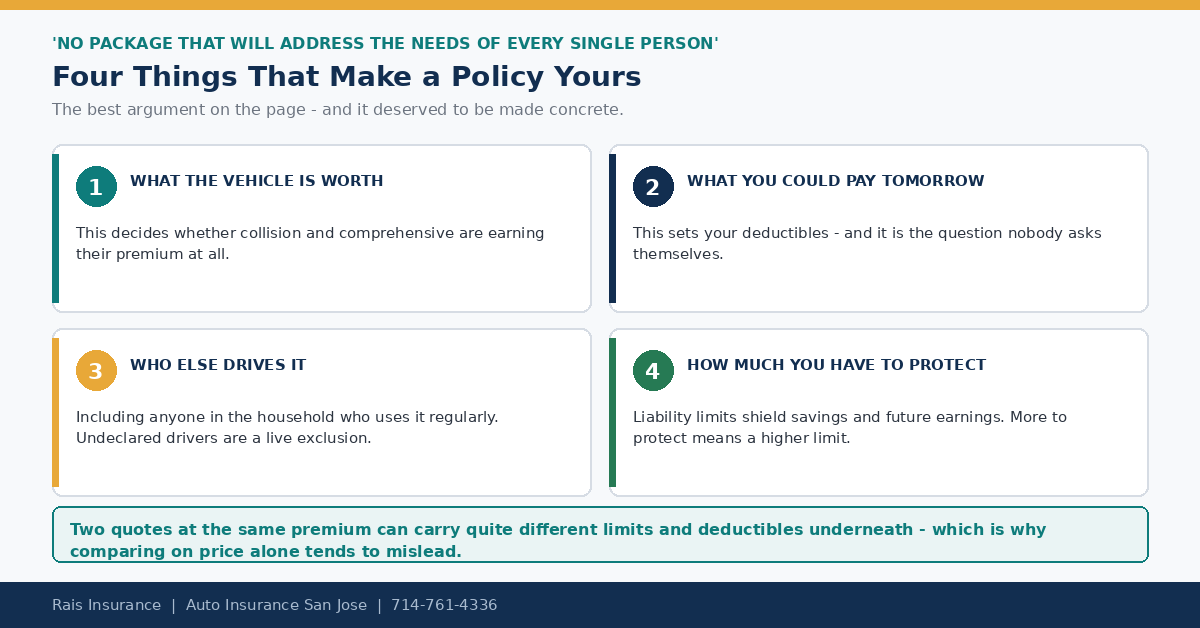
The page’s best argument, made concrete.
This is the best argument on the original page and it is entirely right: there is no package that suits everybody, because people’s circumstances differ. Worth making concrete – four answers do most of the work:
- What the vehicle is worth.This decides whether collision and comprehensive are earning their premium at all.
- What you could pay out of pocket tomorrow.This sets your deductibles, and it is the question nobody asks themselves.
- Who else drives it, including anyone in the household who uses it regularly. Undeclared drivers are a live exclusion.
- How much you have to protect.Liability limits exist to shield savings and future earnings – the more there is, the higher the limit needs to be.
Those four answers change the shape of a car insurance policy far more than any preference does. It is also why comparing on price alone tends to mislead: two quotes at the same premium can carry quite different limits and deductibles underneath.
Driving in San Jose
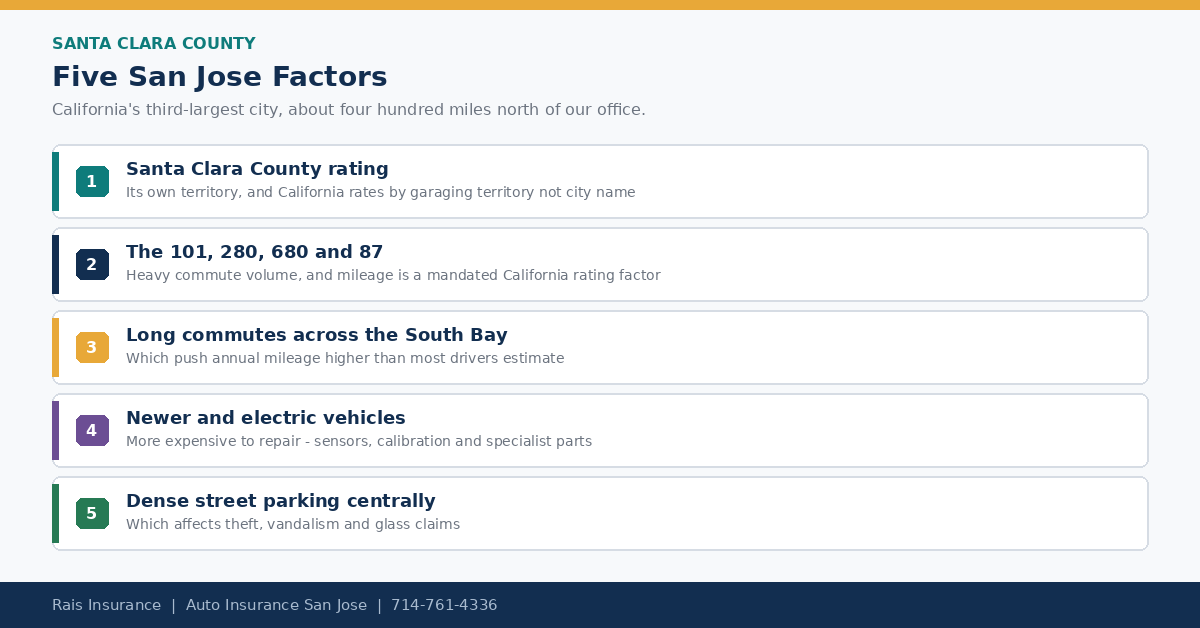
California’s third-largest city, about four hundred miles north of our office.
Five things that shape car insurance San Jose rates specifically, on top of the auto insurance San Jose basics above:
- Santa Clara County rating.Its own territory, and California rates by garaging territory rather than by city name.
- The 101, the 280, the 680 and the 87, and annual mileage is one of the three factors state law requires to weigh most heavily.
- Long commutes across the South Bay, which push annual mileage higher than most drivers estimate.
- A high concentration of newer and electric vehicles, which are more expensive to repair – sensors, calibration and specialist parts all raise claim costs.
- Dense street parking in the central neighbourhoods, which affects theft, vandalism and glass claims.
Finding the Right Plan
The original’s closing promise is a fair one – somebody talking you through the pros and cons of each coverage, so the decision is an informed one rather than a guess. One adjustment to the wording: insurance is not something you invest in. It is a risk transfer – you pay a known amount so an unknown one never lands on you.
As an independent broker we place business across a panel of carriers rather than selling one company’s products, so one set of details gets quoted several times – see the insurance companies we represent. We are not an insurance company; the carrier issues the policy and pays the claim, and there is no fee to you for the comparison. Our office is in Anaheim, so San Jose is served by phone and email.
Auto Insurance in San Jose – Frequently Asked Questions
Does any policy cover ‘any and all incidents’?
No, and it is worth knowing what yours excludes. Wear and tear is never covered on any policy. Nor is mechanical or electrical failure, intentional damage, damage while the vehicle is used for delivery or hire, or damage caused by an excluded driver. A policy is a defined set of coverages, each with a limit and most with a deductible.
What does collision actually pay?
The lower of the repair cost or the vehicle’s actual cash value, less your deductible. The original version of this page says it pays for ‘repairing or replacing’ the damaged parts, which is right up to a point – but if the repair would cost more than the car is worth, the carrier declares it a total loss and pays the value instead.
What is actual cash value?
What the vehicle was worth immediately before the loss – its market value, not what you paid or what a replacement costs today. It is the ceiling on every collision and comprehensive claim, and it falls every year, which is why physical damage cover buys progressively less as a car ages.
What happens if repairs cost more than the car is worth?
The vehicle is declared a total loss. Rather than repairing it, the carrier pays you its actual cash value less your deductible, and takes the vehicle. This is the outcome that surprises people most, because a policy described as covering ‘repair or replacement’ can end with neither.
Does medical payments cover funeral expenses?
Yes, and the original version of this page is right to mention it – most pages do not. Medical payments covers medical costs for you and your passengers without anyone having to establish fault, and death benefits are part of what it does. The limits are modest and the coverage is inexpensive.
What is missing from the list on this page?
Three things. Property damage liability, which California requires alongside bodily injury liability. Comprehensive, which covers theft, fire, weather, vandalism and animal strikes. And uninsured and underinsured motorist cover, which is the only thing that responds when the driver who hits you has no insurance.
Do I need uninsured motorist cover if I have collision?
They answer different questions. Collision repairs your vehicle regardless of fault, subject to your deductible. Uninsured motorist covers your injuries and losses when the at-fault driver has nothing – which collision does not address at all. In a fault-based state, one does not substitute for the other.
Is there really no standard package?
The original is right about this and it is the best argument on the page. What varies is not preference but circumstance: what the vehicle is worth, what you could pay out of pocket, who else drives it, and how much you have to protect. Those four answers change which coverages make sense and at what limits.
Does my policy cover the car if I use it for deliveries?
Usually not. Personal auto policies commonly exclude vehicles used to carry goods or passengers for payment, which includes delivery driving. It is one of the more expensive exclusions to discover at claim time, and it is worth raising before rather than after.
How do I get a San Jose auto insurance quote?
Call Rais Insurance on 714-761-4336 or email rai@raisinsurance.com. Our office is in Anaheim, so San Jose is served by phone and email. We are an independent broker, so one set of details is quoted across several carriers, and there is no fee to you for the comparison.
Get a Car Insurance Quote in San Jose
contact Rais Insurance on 714-761-4336 or email rai@raisinsurance.com.
One question worth answering before you call about car insurance: what your vehicle is currently worth. It decides whether collision and comprehensive still make sense, and it is the number most people have not looked up recently.
