
Auto Insurance Cypress California
Plenty can happen on the road that leaves you with a damaged car and an unexpected bill. Collisions, animals and unexpected potholes are three of the commonest – and the interesting thing about that list, which the original version of this page names without following up, is that each one falls to a different coverage.
So that is where this car insurance guide starts. If you are comparing auto insurance Cypress options, knowing which part of a policy answers which hazard is more useful than a list of product names.
Three Road Hazards, Three Different Answers
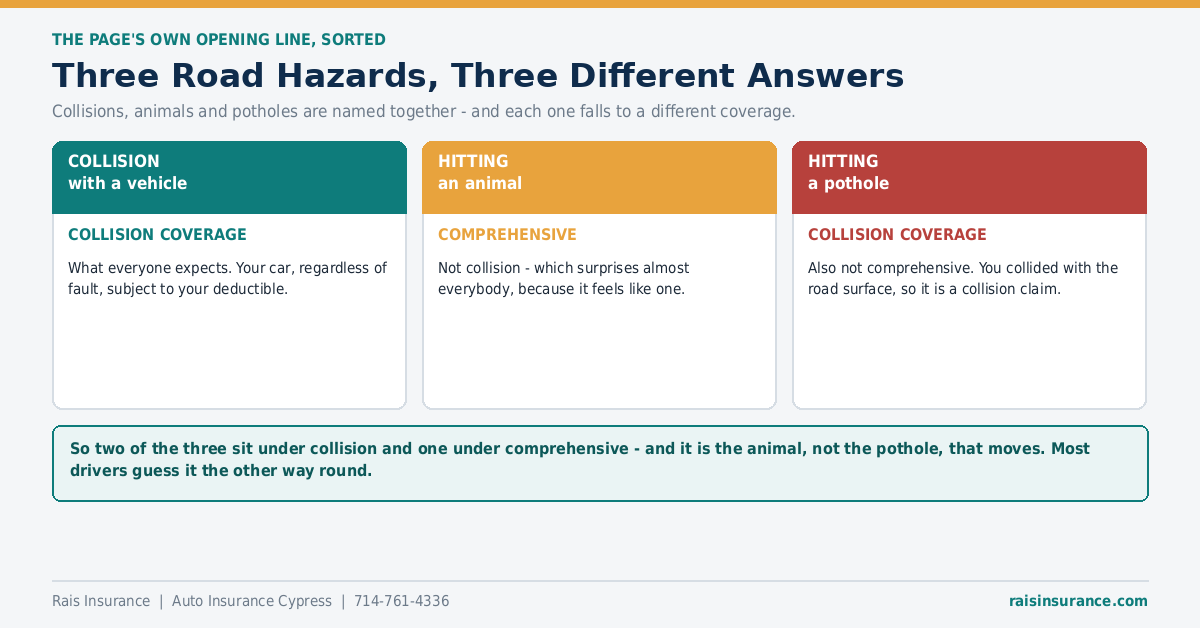
- Colliding with another vehicle – collision coverage. What everyone expects. It repairs your car regardless of fault, subject to your deductible.
- Hitting an animal – comprehensive, not collision. This surprises almost everybody, because it feels like a collision. It generally works in your favour: comprehensive claims are often treated more leniently at renewal, and comprehensive usually carries the lower premium of the two. See what comprehensive coverage actually covers.
- Hitting a pothole – collision again, not comprehensive. The reasoning is that you collided with the road surface.
So two of the three sit under collision and one under comprehensive – and it is the animal, not the pothole, that moves. Most drivers guess it the other way round.
Potholes – the one people get wrong most
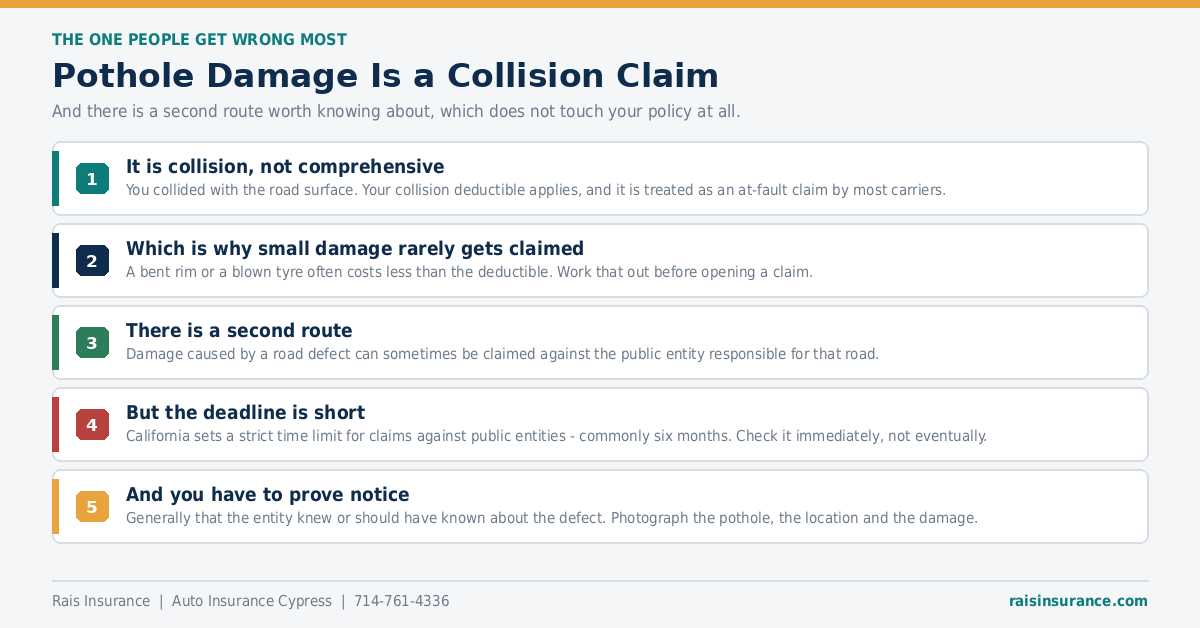
Worth going further on this, because it is one of the commonest car insurance questions there is, and there are two routes:
- It is a collision claim, your collision deductible applies, and most carriers treat it as an at-fault claim – which means it can affect your renewal.
- So small damage often should not be claimed at all. A bent rim, a blown tyre or a knocked alignment frequently costs less than the deductible. Work that out first – see when collision and comprehensive stop earning their premium.
- There is a second route. Damage caused by a defect in a public road can sometimes be claimed against the public entity responsible for maintaining it, which does not touch your own policy at all.
- But the deadline is short. California sets a strict time limit for claims against public entities, considerably shorter than an ordinary claim. Check it immediately rather than eventually.
- And you generally have to show notice – that the entity knew or should have known about the defect. Photograph the pothole, the location and the damage at the time.
Note that collision is optional cover. A liability-only policy will not respond to a pothole, an animal or your own vehicle at all.
Uninsured and Underinsured Motorist Cover
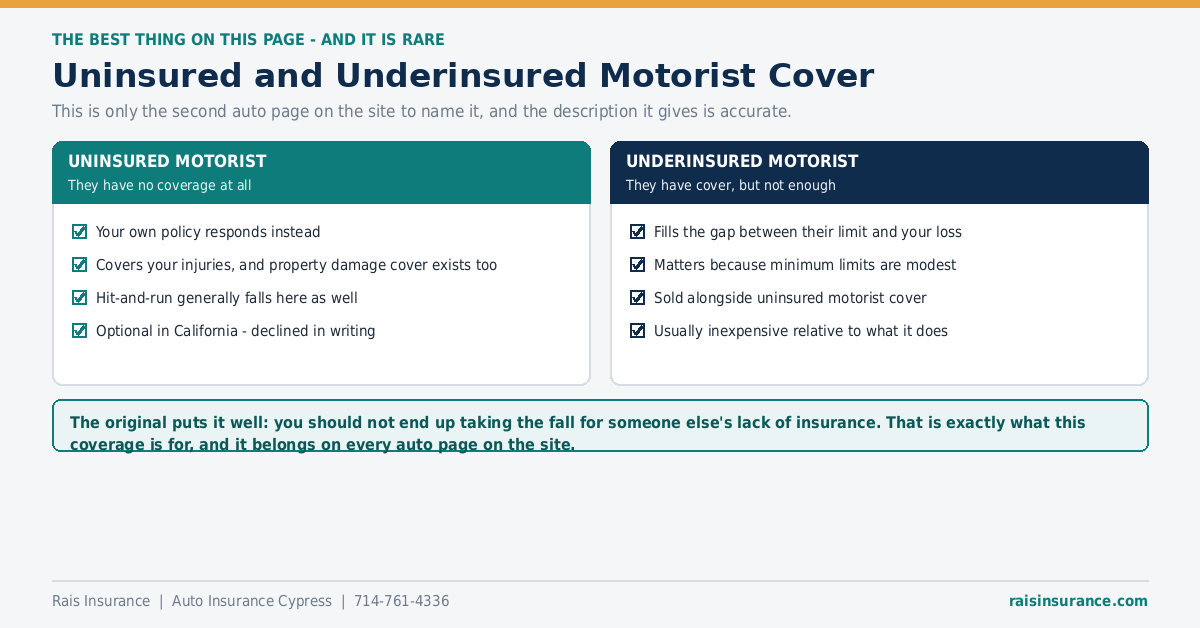
The original names this and describes it accurately – even if the person you got into an accident with is not insured, you will not be penalised for it. That is exactly right, and it is worth expanding because it is the most consequential optional coverage in an at-fault state:
- Uninsured motorist responds when the other driver has no coverage at all. Your own policy pays instead of theirs. A hit-and-run generally falls here too, since an unidentified driver is treated much like an uninsured one.
- Underinsured motorist is the other half. It fills the gap when the at-fault driver does have insurance but not enough of it. Because California’s minimum limits are modest, that gap is real – see how liability limits actually work.
Both are optional on a California auto insurance policy, and a carrier must offer them and obtain your decline in writing. The reason they matter here is structural: because California is an at-fault state, what you recover depends on the other driver’s limits. A driver with nothing leaves you nothing to claim against, and this is the only thing that fills that.
One Correction: No-Fault Coverage
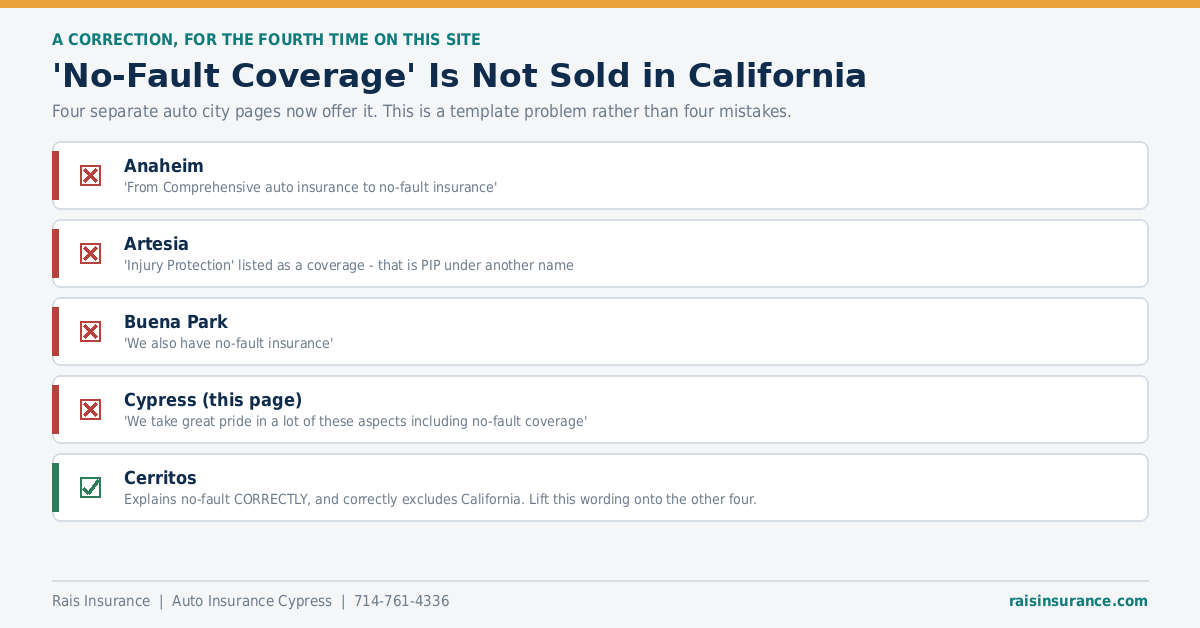
The original lists no-fault coverage among what is offered. That needs correcting: California does not have no-fault auto insurance.
California is an at-fault state – the driver responsible for a collision is responsible for the cost, and their liability coverage answers the claim. No-fault systems exist in about a dozen other states, where each carrier pays its own client regardless of blame and Personal Injury Protection is required. PIP is not sold here. See California is an at-fault state.
The instinct behind the sentence is sound, though, and this page already contains the right answer to it. What protects you when the accident was not your fault and the other driver cannot pay is uninsured and underinsured motorist cover – which is named two paragraphs earlier.
What Is Actually Required, and What Is Optional
One thing the original never mentions: liability is the only car insurance coverage California requires – bodily injury and property damage. Everything else on this page is a choice:
- Required: bodily injury liability and property damage liability.
- Optional: collision, comprehensive, medical payments, and uninsured and underinsured motorist cover.
- Effectively required by a lender: collision and comprehensive, while a vehicle is financed or leased.
The current minimum limits and the penalties for driving without cover are on our auto insurance in California page.
Driving in Cypress
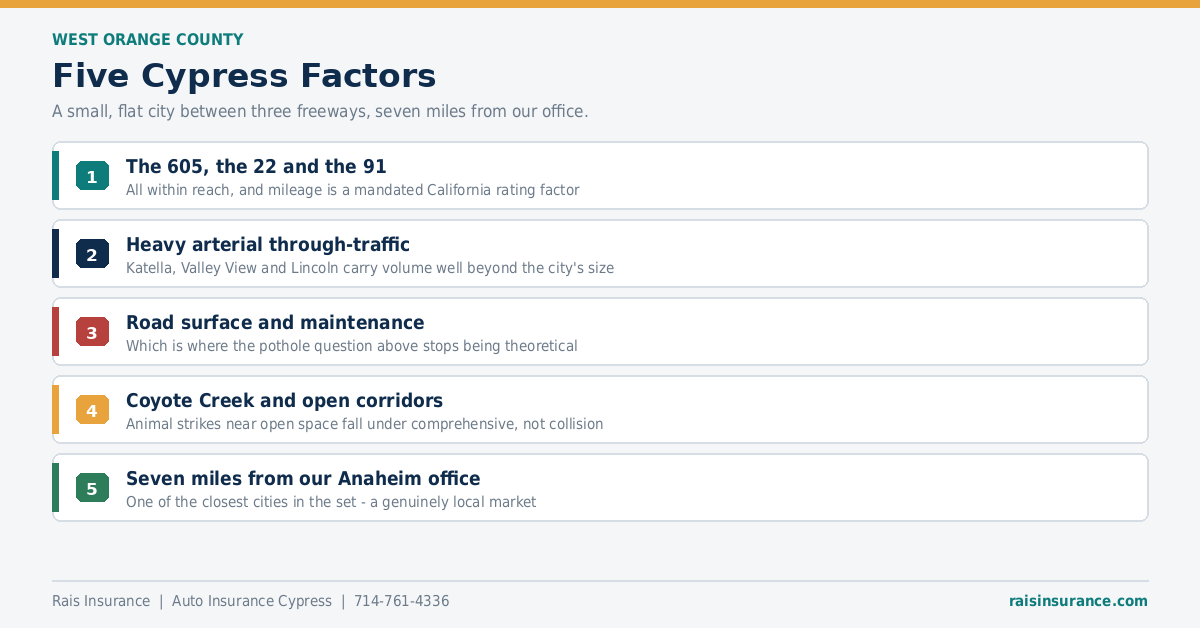
Five things that shape car insurance Cypress rates specifically:
- The 605, the 22 and the 91. All within reach, and annual mileage is one of the factors California law requires to weigh most heavily in your rate.
- Heavy arterial through-traffic. Katella, Valley View and Lincoln carry volume well beyond what the city’s size suggests.
- Road surface and maintenance, which is where the pothole question above stops being theoretical.
- Coyote Creek and the open corridors. Animal strikes near open space fall under comprehensive rather than collision.
- About seven miles from our Anaheim office – one of the closest cities in our set, and a genuinely local market for us.
Being Ready for Whatever the Road Does
The original’s closing point is a fair one: you cannot know what the road or another driver will do, so the useful work is being prepared for the range rather than the average. What that means in practice is knowing which auto insurance coverages you actually hold and which you have declined.
As an independent broker we place business across a panel of carriers rather than selling one company’s products – so one set of details gets quoted several times. We are not an insurance company; the carrier issues the policy and pays the claim, and there is no fee to you for the comparison. See the insurance companies we represent.
Auto Insurance in Cypress – Frequently Asked Questions
Q1. Is pothole damage covered by insurance?
Yes, under collision coverage – not comprehensive, which is where most drivers expect it. The reasoning is that you collided with the road surface. Your collision deductible applies, and most carriers treat it as an at-fault claim, so it can affect your renewal. Collision is optional cover, so a liability-only policy will not respond at all.
Q2. Should I claim for pothole damage?
Often not. A bent rim, a blown tyre or a damaged alignment frequently costs less than a collision deductible, and the claim can affect your renewal for years. Work out the repair cost against your deductible before opening one. If the damage is severe – suspension, wheel, bodywork – the calculation changes.
Q3. Can I claim against the city for pothole damage?
Sometimes. Damage caused by a defect in a public road can be claimed against the public entity responsible for maintaining it, which does not touch your own policy. Two things matter: California sets a strict and short deadline for claims against public entities, and you generally have to show the entity knew or should have known about the defect. Photograph the pothole, the location and the damage immediately.
Q4. Is hitting an animal collision or comprehensive?
Comprehensive – which surprises almost everybody, because it feels like a collision. It generally works in your favour: comprehensive claims are often treated more leniently at renewal than at-fault collision claims, and comprehensive usually carries the lower premium of the two.
Q5. What is uninsured motorist coverage?
It responds when the driver who hits you has no insurance at all – your own policy pays instead of theirs. The original version of this page puts it well: you should not end up taking the fall for somebody else’s lack of insurance. It is optional in California, and a carrier must obtain your decline in writing.
Q6. What is underinsured motorist coverage?
The other half of the same idea. It fills the gap when the at-fault driver does have insurance but not enough of it to cover your loss. Because California’s minimum limits are modest, that gap is real – a serious injury claim can exceed a minimum policy without difficulty.
Q7. Does uninsured motorist cover a hit-and-run?
Generally yes, since an unidentified driver is treated much like an uninsured one. Reporting requirements apply and vary by carrier and circumstance, so report it to the police and to your insurer promptly rather than waiting to see whether the other driver is traced.
Q8. Is there no-fault coverage in California?
No. California is an at-fault state – the driver responsible pays, through their liability coverage. No-fault systems exist in about a dozen other states, where each carrier pays its own client regardless of blame and Personal Injury Protection is required. PIP is not sold in California.
Q9. What coverage is actually required in California?
Liability – bodily injury and property damage – and nothing else. Collision, comprehensive, medical payments and uninsured motorist are all optional, though a lender will usually require collision and comprehensive while a vehicle is financed. Our main auto insurance page covers the current minimum limits.
Q10. How do I get a Cypress auto insurance quote?
Call Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or visit 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801 – about seven miles away. We are an independent broker, so one set of details is quoted across several carriers, and there is no fee to you for the comparison.
Get a Car Insurance Quote in Cypress
contact Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or visit 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801.
Two lines worth checking on your current car insurance Cypress policy: whether you carry collision at all, and whether you carry uninsured motorist cover. Both are optional, and both are the ones people discover they declined at exactly the wrong moment.
FIND US ON THE MAP