

Auto Insurance Orange California
Auto insurance for Orange drivers, quoted across several carriers by Rais Insurance.Moving to Orange? It sits about ten minutes from Anaheim and well clear of central Los Angeles, and it is a good place to land once the boxes are unpacked. Sorting out the car insurance Orange residents can rely on – auto insurance Orange newcomers ask about first – is one of the last hoops – after the utilities, the registrations and the schools – and it is the one where a wrong assumption costs the most. Getting car insurance in Orange CA right from day one avoids a costly correction later.
We are also four miles up the road, which makes Orange the closest city in our whole service area. We quote auto insurance Orange CA drivers need across several carriers rather than just one.
Arriving in California
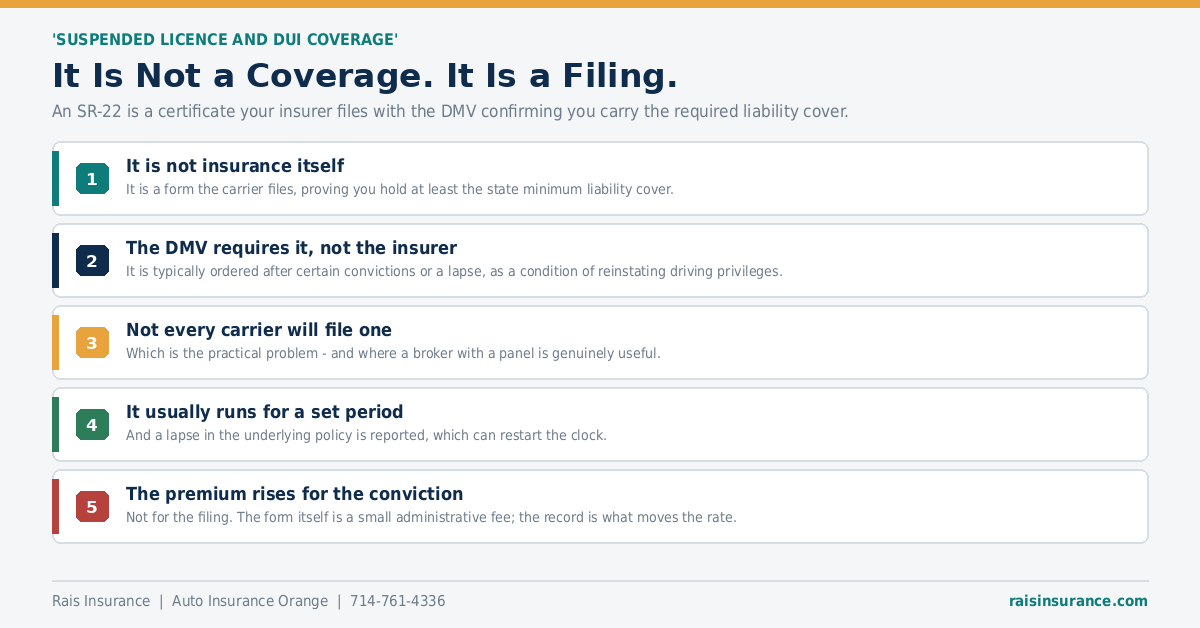
If you are coming from another state, four things change about your car insurance:
- You have a deadline. California expects new residents to obtain a state driver’s licence and register the vehicle within a set period of establishing residency.
- Your existing policy will not carry over. Cover has to meet California requirements and be written for a California-garaged vehicle.
- The rate is built on the new address, not the old one – rates here are set by garaging territory, and the difference can go either way. See what changes when you move.
- No-fault does not come with you. If you have moved from one of the states that runs a no-fault system, personal injury protection is not sold in California – see California is an at-fault state.
That last one catches people out most. If you are used to your own policy paying your injuries regardless of blame, that is not how it works here – medical payments cover, your health plan and the at-fault driver’s liability do that work between them. This is one of the most common surprises for new residents comparing California auto insurance Orange options against their old state’s policy.
How Much Coverage Do You Need?
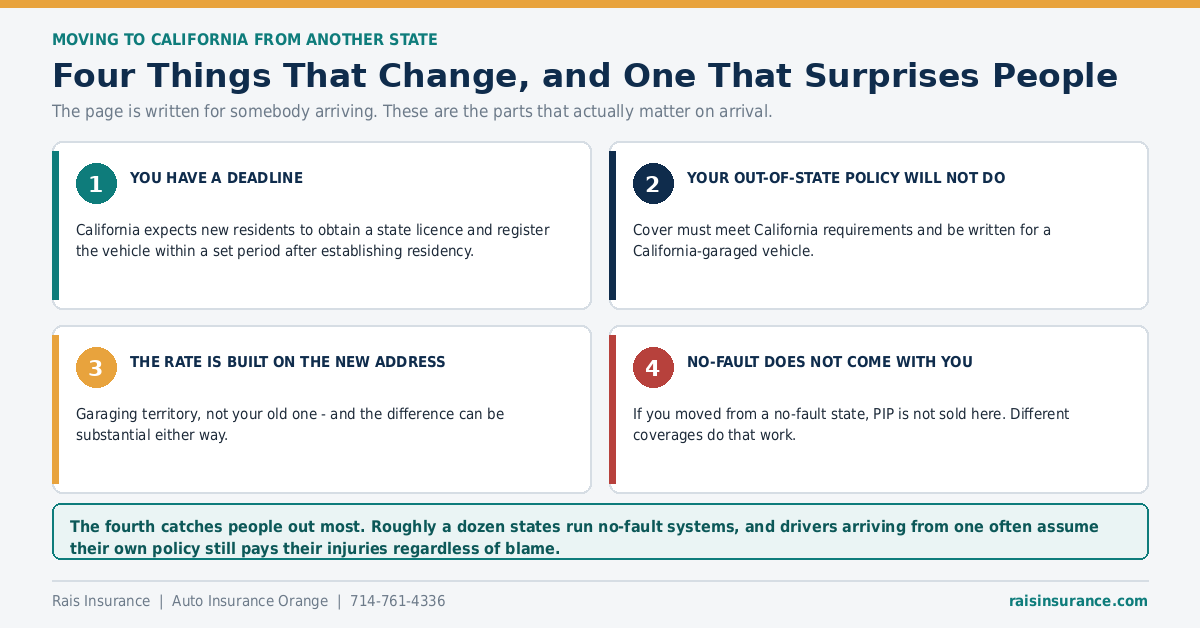
The original version of this page frames the auto insurance question well – it is tempting to pinch pennies, and the minimum is rarely the right answer. One correction on the detail though: it refers to “minimum coverage for collision and liability“, and collision is never part of California’s minimum. The requirement is:
- Bodily injury liability – required. Injuries you cause to other people.
- Property damage liability – required. Damage you cause to their vehicle or property.
- Collision – optional, though a lender will require it while a vehicle is financed.
- Comprehensive – optional.
- Medical payments – optional.
- Uninsured motorist and underinsured motorist cover – optional, and a carrier must obtain your decline in writing. It is the only thing that responds when the at-fault driver has no insurance.
The current minimum limits are on our auto insurance in California page. Owners of higher-value or modified vehicles often ask us about agreed value car insurance Orange County CA coverage rather than the standard depreciation-based payout.
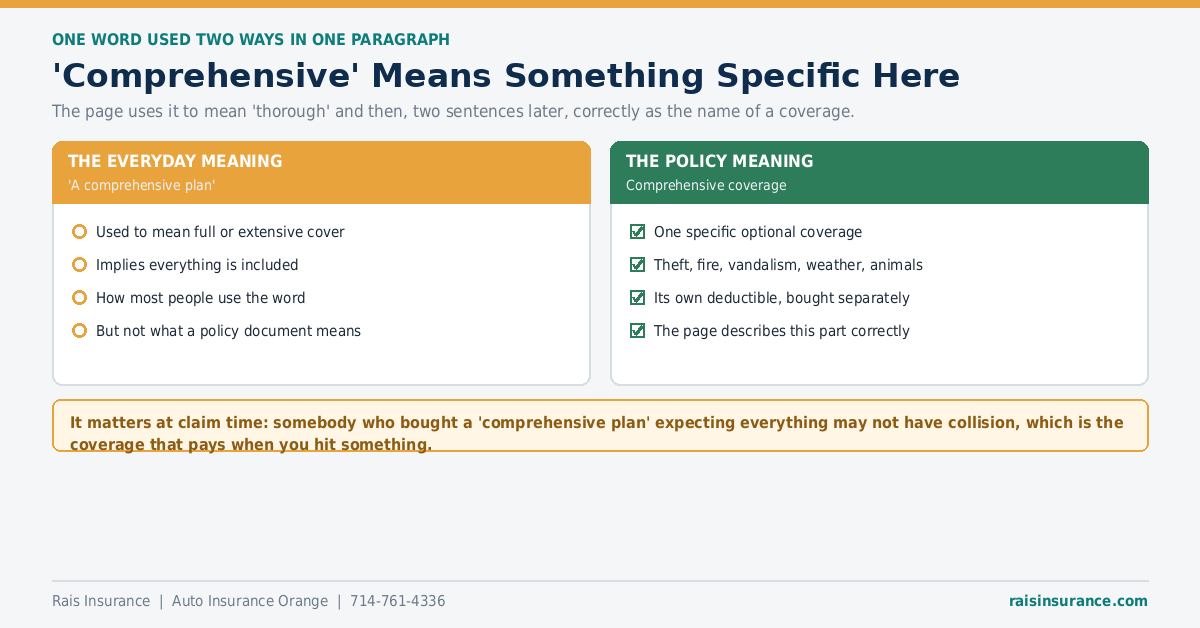
A note on the word ‘comprehensive’
The original uses it in two senses within one paragraph – first to mean a thorough policy, then correctly as the name of a coverage. Both uses are natural in ordinary speech, but only the second is what appears on a declarations page:
- Comprehensive is one specific optional coverage with its own deductible.
- It covers theft, fire, vandalism, weather, falling objects and animal strikes – and the original names animal collisions, weather and vandalism, all correctly. See what comprehensive coverage actually covers.
- It does not cover a collision. That is a separate coverage, bought separately. For classic or exotic vehicles, agreed value car insurance Orange County CA options can also be arranged instead of standard actual cash value settlement.
This matters at claim time: somebody who bought a “comprehensive plan” expecting everything might not hold collision – which is the coverage that pays when you hit something.
Driving After a Suspension or a DUI
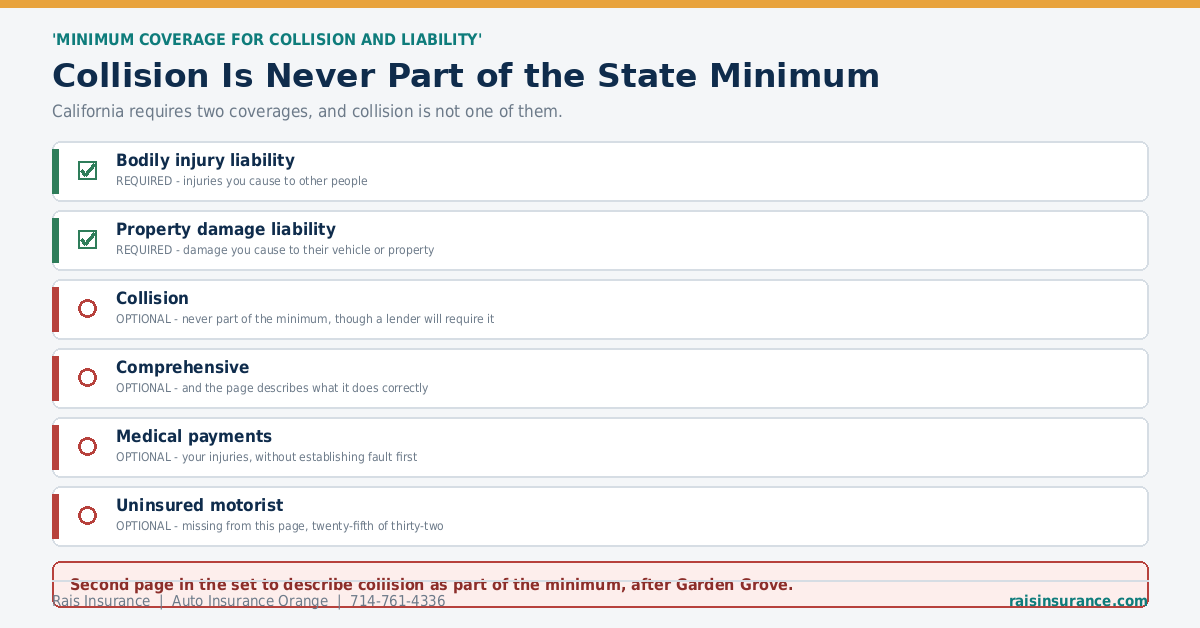
The original offers “suspended licence and DUI coverage”, and the intent behind that is right – this is business we can place where many will not. The wording needs correcting though, because there is no such thing as DUI insurance:
- What exists is an SR-22, which is not insurance at all. It is a certificate your carrier files with the DMV confirming you hold at least the required liability coverage.
- The DMV requires it, not the insurer – typically after certain convictions or a lapse in cover, as a condition of reinstating driving privileges.
- Not every carrier will file one. That is the practical difficulty, and it is where working a panel genuinely helps rather than approaching carriers individually and collecting declines.
- It runs for a set period, and the policy behind it must stay continuously in force. A lapse is reported, which can extend the requirement.
- The filing fee itself is small. What raises the premium is the conviction or lapse on your driving record – which is one of the three factors California requires carriers to weigh most heavily.
So the honest version of the offer is better than the original: an ordinary policy, plus the filing, placed with a carrier that writes this business. See the insurance companies we represent. For classic or exotic vehicles, agreed value car insurance Orange County CA options can also be arranged instead of standard actual cash value settlement.
Policies for Young Drivers
The original mentions cover for teens starting out on their own, which is worth expanding briefly. California rates on years of driving experience rather than age as such, so the premium falls progressively as a new driver builds a clean record rather than dropping at a particular birthday.
Three things reduce the cost meaningfully: asking how the new driver will be assigned to a vehicle (carriers rate by assigned car), asking for the good student discount, which is never applied automatically, and reviewing your liability limits at the same time – the riskiest period is exactly when a minimum limit is least adequate. More on our adding a young driver to your policy page. Young driver policies are one of the areas where car insurance Orange CA rates vary the most between carriers, which is why comparing matters.
Driving in Orange
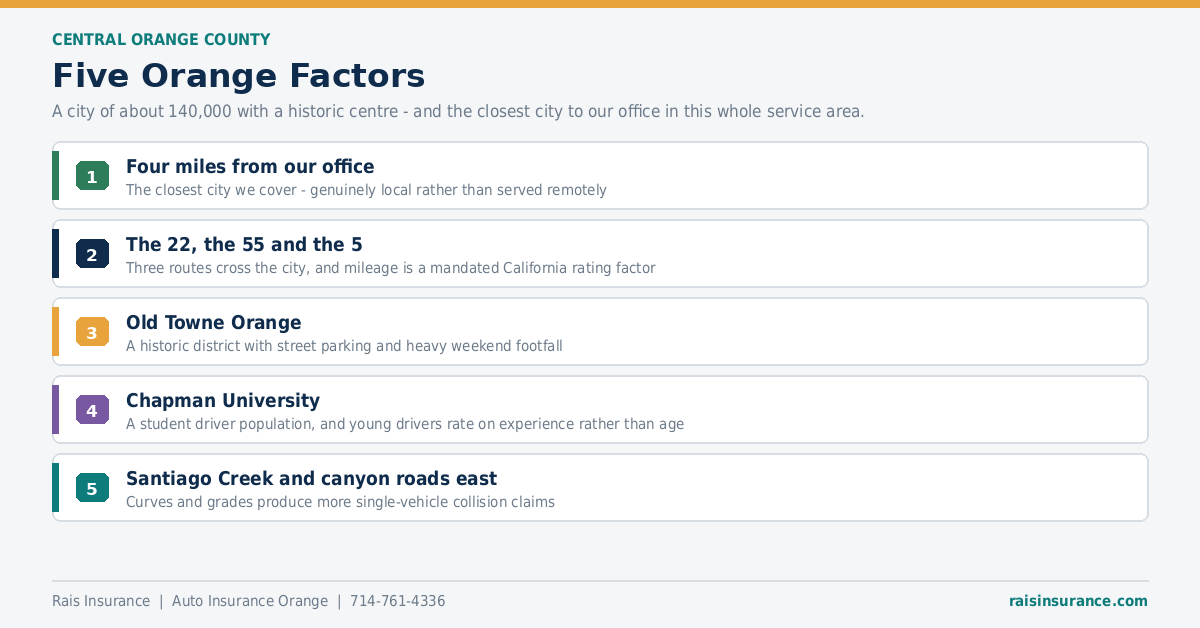
Five things that shape car insurance Orange rates specifically, on top of the auto insurance Orange basics above:
- About four miles from our office – the closest city we cover, and a genuinely local market rather than one served remotely.
- The 22, the 55 and the 5 all cross the city, and annual mileage is one of the three factors California law requires to weigh most heavily.
- Old Towne Orange, a historic district with street parking and heavy weekend footfall – which is where theft, vandalism and glass claims come from.
- Chapman University, and a student driver population that rates on experience rather than age.
- Santiago Creek and the canyon roads east, where curves and grades produce more single-vehicle collision claims than flat suburban driving.
One correction on the original’s local detail: the tourist and seasonal traffic it describes belongs to Anaheim, where Disneyland is – not to Orange itself. Orange’s own busy periods come from Old Towne and the university calendar. These local factors are exactly what shape car insurance in Orange CA pricing, more than a generic statewide estimate ever could. They are also the details that move car insurance Orange CA premiums up or down, not generic statewide averages.
Making This Part Easier
The original’s promise is the right one: you have a great deal to organise, so this should be the straightforward part. What that means in practice is that we do the car insurance comparison rather than handing you a list of carriers to work through.
As an independent broker we place business across a panel of carriers rather than selling one company’s products, so one set of details gets quoted several times. We are not an insurance company; the carrier issues the policy and pays the claim, and there is no fee to you for the comparison. That comparison is how we keep car insurance in Orange CA quotes competitive without you doing the legwork yourself. Car insurance quotes in Orange, CA from our panel are free and carry no obligation to buy.
Auto Insurance in Orange – Frequently Asked Questions
Q1. What is an SR-22?
Not a type of insurance – it is a certificate your carrier files with the California DMV confirming you hold at least the state minimum liability coverage. It is typically required after certain convictions or a lapse in cover, as a condition of reinstating driving privileges. The insurance behind it is an ordinary policy; the SR-22 is the proof. This is the most common reason Orange drivers first call us about sr22 insurance orange city.
Q2. Is there such a thing as DUI insurance?
No, and the distinction matters. There is no separate product that covers you for a DUI. What exists is an ordinary auto policy plus an SR-22 filing where the DMV requires one. What changes after a conviction is the rate and which carriers will write you – not the coverage you are buying.
Q3. Do all insurers file SR-22s?
No, and that is the practical difficulty. Some carriers decline the business altogether and others will write it at a price. This is one of the clearer cases where an independent broker earns their place, because we can work a panel rather than have you approach carriers one at a time and collect declines. That panel is exactly what makes sr22 insurance orange city placements possible when a direct carrier says no.
Q4. How long is an SR-22 required?
For a set period determined by the DMV in connection with the underlying matter. What catches people out is that the policy behind it has to stay continuously in force – a lapse is reported to the DMV, which can extend the requirement or affect your driving privileges.
Q5. Does an SR-22 itself cost much?
The filing fee is small. What raises the premium is the conviction or lapse that led to it, which sits on your driving record and is one of the three factors California requires carriers to weigh most heavily. Those two things are often confused – it is the record, not the form.
Q6. Is collision part of California’s minimum coverage?
No. California requires bodily injury liability and property damage liability. Collision and comprehensive are both optional, though a lender will usually require them while a vehicle is financed. The original version of this page refers to ‘minimum coverage for collision and liability’, which is not how the requirement works.
Q7. What does comprehensive actually cover?
Theft, fire, vandalism, weather, falling objects and animal strikes – damage that does not come from your vehicle hitting something. The original names animal collisions, weather and vandalism, and all three are correct. Note that comprehensive is one specific coverage rather than a synonym for a thorough policy. If your vehicle is a classic or highly customised build, ask us about agreed value car insurance Orange County CA coverage at the same time.
Q8. I am moving to California – what do I need to do?
New residents are expected to obtain a California driver’s licence and register the vehicle within a set period after establishing residency, and your out-of-state policy will not carry over – cover has to meet California requirements and be written for a California-garaged vehicle. The rate is built on your new address rather than your old one. It’s the first thing to sort out when shopping California auto insurance Orange quotes as a new arrival.
Q9. I moved from a no-fault state – does that change anything?
Yes, and it surprises people. California is a fault-based state and does not sell personal injury protection. If you are used to your own policy paying your injuries regardless of blame, that is not how it works here – medical payments coverage, your health plan and the at-fault driver’s liability do that work between them.
Q10. How do I get an Orange auto insurance quote?
Call Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or visit 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801 – about four miles away, which makes Orange the closest city in our service area. We are an independent broker, so one set of details is quoted across several carriers. That is how we keep auto insurance Orange CA pricing competitive for every driver who calls us.
Get a Car Insurance Quote in Orange
contact Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or come and see us at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801 – about four miles away. We return car insurance quotes in Orange, CA usually within one business day of receiving your details.
Ask for car insurance quotes in Orange, CA that already account for an SR-22 filing, if you need one, rather than requesting it as an afterthought. If a filing is needed, say so at the start rather than partway through.
It changes which carriers can be approached, and knowing that first saves working through a list that was never going to write the business.
FIND US ON THE MAP
