
The Insurance Companies We Represent
Thirteen carriers, one application – what an independent broker’s panel means for you.Rais Insurance is an independent insurance agent based in Anaheim, California. We hold appointments with a number of insurance companies rather than working for one, which means a single conversation with us reaches several markets at once.
That distinction is worth a page of its own, because it changes what can be offered to you – particularly when a carrier declines your risk, issues a non-renewal, or raises your rate at renewal.
Independent Broker or Captive Agent?
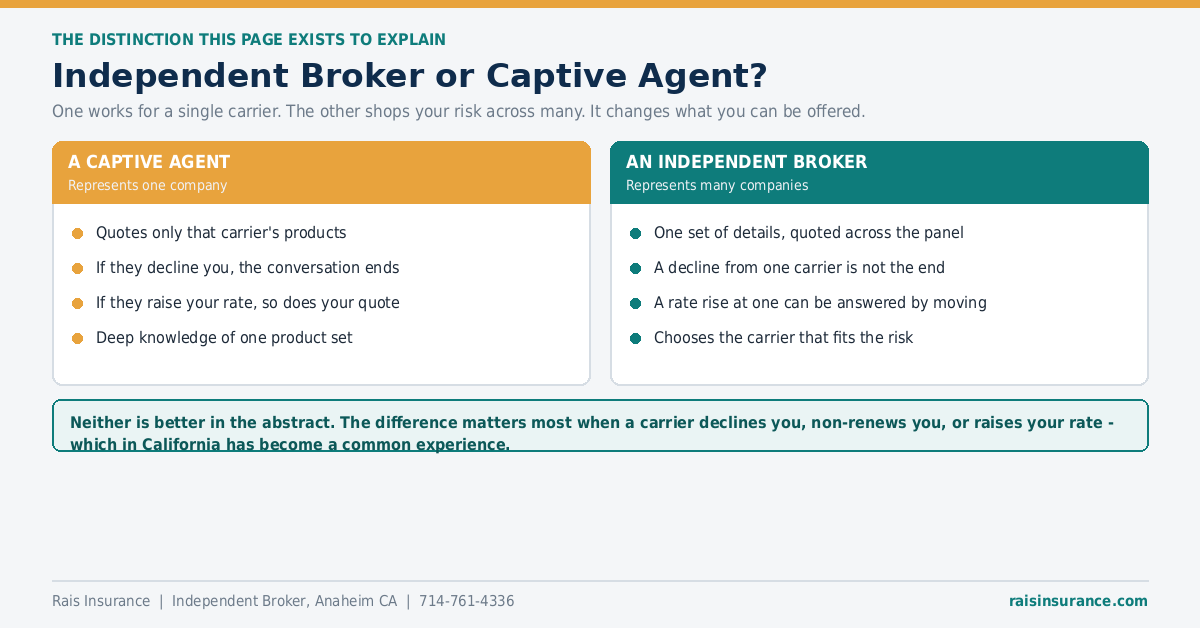
There are two kinds of insurance agent, and most people never learn which one they are talking to.
A captive agent represents one company. They quote that carrier’s products, and their knowledge of those products is usually excellent. But if that carrier declines your risk, the conversation ends there. If that carrier raises its rates, your quote rises with it.
An independent broker represents many. We take one set of details from you and put them to the carriers whose appetite fits your situation. A decline from one is not a decline from all, and a rate increase at one can be answered by moving to another.
Neither model is better in the abstract. The difference matters most at the moments when it is hardest to shop for yourself – which, in the California market, has become a common experience rather than a rare one.
The Companies We Represent

Grouped by what each is generally used for:
Personal auto and home
- Mercury Insurance Group – see our authorized Mercury Insurance agent
- Progressive Insurance
- Kemper Insurance
- Foremost Insurance
- National General Insurance
- Bristol West Insurance
- Bamboo Insurance
- Aegis Insurance
- First Capital Insurance
- Delos Insurance
- Heritage Insurance
Commercial
- Guard Insurance
- Three Insurance
- Liberty Insurance
Carrier appointments change over time as companies enter markets, leave them, or restructure – so this list is reviewed periodically. If you are looking for a particular company, ask us: what is available today is a better answer than what was available when a page was written.
When Having a Panel Actually Matters
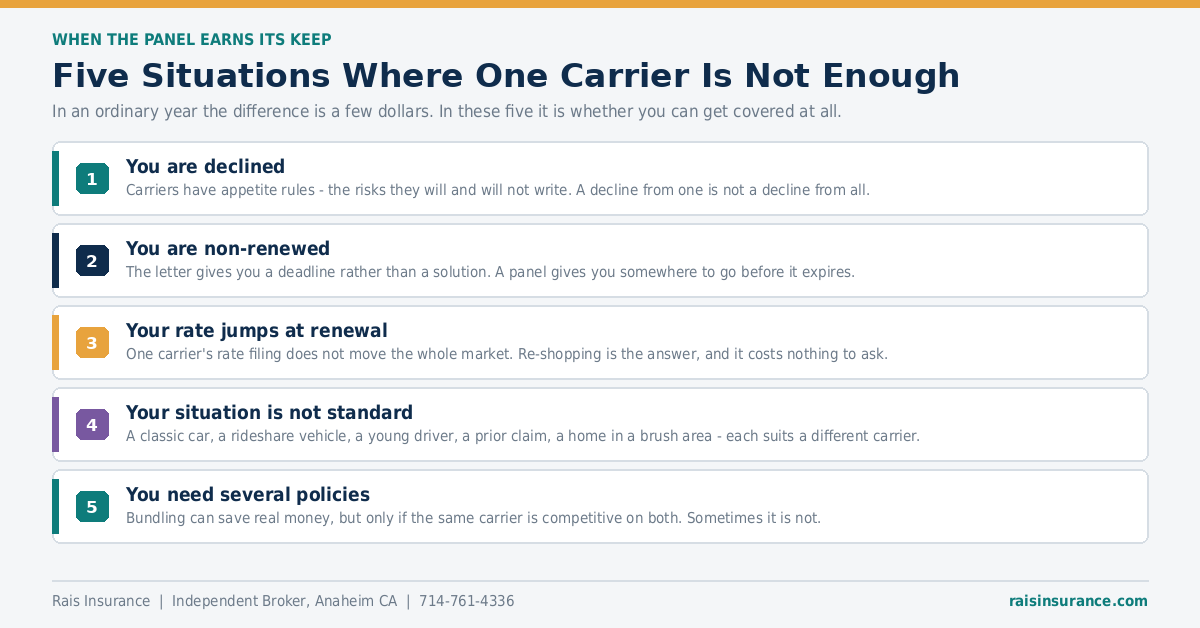
In an ordinary renewal year the practical difference between one carrier and fourteen is a modest saving. In five situations it is the difference between being covered and not:
- You are declined. Every carrier has an appetite – the classes of risk it wants and the ones it will not write. A decline tells you about that carrier’s appetite, not about the market.
- You are non-renewed. A non-renewal notice gives you a deadline rather than a solution. A panel gives you somewhere to go before the date on it.
- Your rate jumps at renewal. One company’s rate filing does not move the whole market. Re-shopping costs nothing to ask about, and it is the single most effective thing most people never do.
- Your situation is not standard. A rideshare vehicle, a young driver, a prior claim, a home in a brush area – each of those suits a different carrier, and a panel lets us put your details to the ones most likely to say yes.
- You need several policies. Bundling can save real money, but only when the same carrier happens to be competitive on both lines. Sometimes it is not, and it is worth knowing which case you are in.
What Happens When You Call
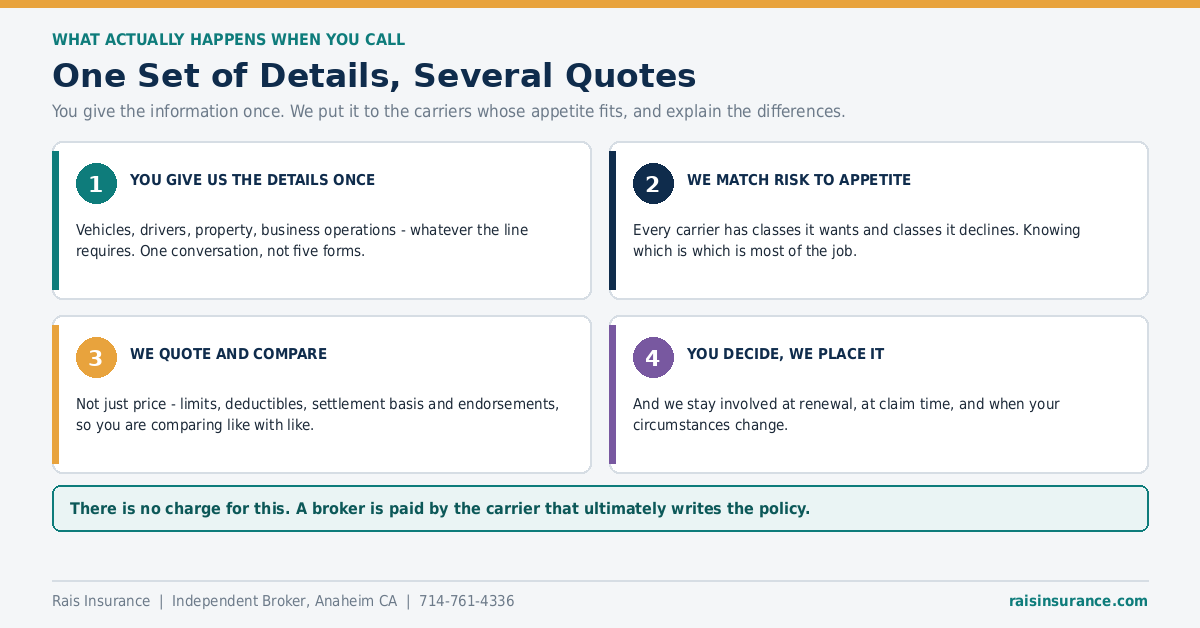
- You give us the details once. Vehicles, drivers, property, business operations – whatever the line requires. One conversation rather than five separate forms.
- We match your risk to carrier appetite. Knowing which companies want which risks is most of the actual job, and it is what stops you being quoted by carriers who were never going to write you.
- We quote and compare properly. Not just price – limits, deductibles, settlement basis and endorsements, so you are comparing like with like rather than two numbers.
- You decide, and we place it. Then we stay involved: at renewal, at claim time, and whenever your circumstances change.
There is no charge to you for any of this. A broker is compensated by the carrier that ultimately writes the policy, so the price you pay is the carrier’s price.
What We Place Across the Panel
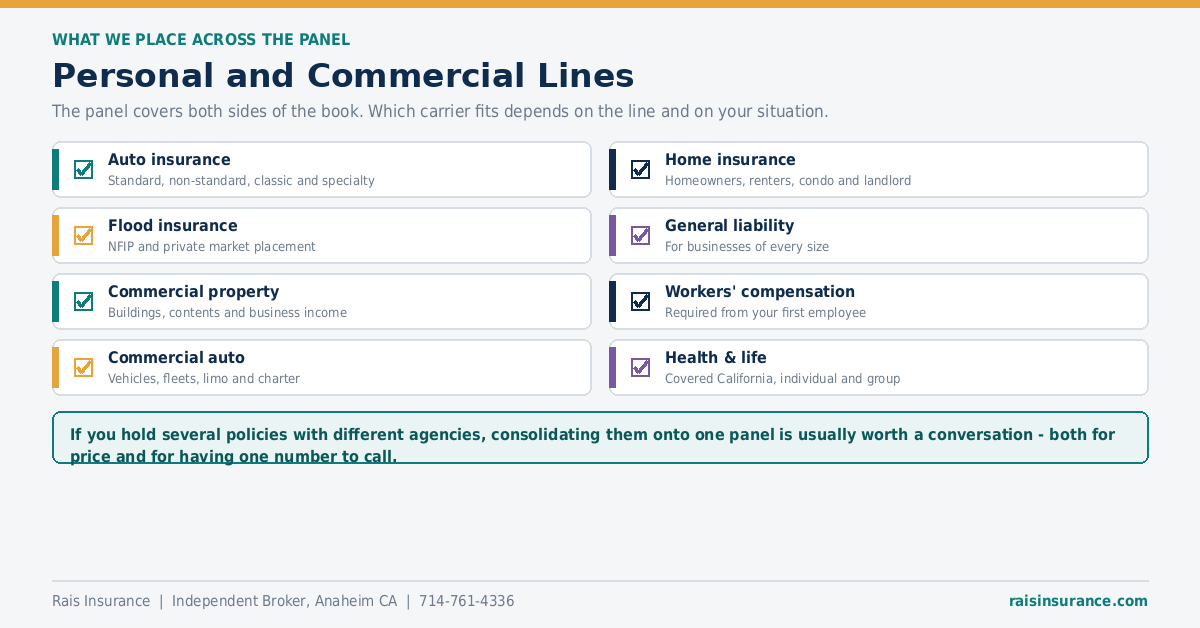
- auto insurance in California – standard, non-standard, classic and specialty.
- home insurance in California and renters insurance.
- flood insurance in California – NFIP and private market.
- business insurance in California – general liability, commercial property, workers’ compensation and commercial auto.
- Covered California and health insurance, plus life cover.
If you currently hold policies with several different agencies, consolidating them onto one panel is usually worth a conversation – both for the price and for having a single number to call when something happens.
About Rais Insurance
We are an independent insurance broker based at 2612 W. Lincoln Avenue in Anaheim, serving Orange County, Los Angeles County and the wider California market. Our clients range from households buying a first auto policy to businesses placing general liability, commercial property and workers’ compensation programmes.
As an insurance agency Anaheim residents and business owners can walk into, we would rather have the conversation about what you actually need than push a product. In practice that often means telling somebody their current policy is fine, or that a coverage they were sold is not doing what they think it is.
It also means being straightforward about the market. Availability in California has been genuinely difficult in some lines and some locations, and an independent insurance agent with a panel is better placed to work through that than a single carrier – but nobody can place a risk no carrier will write. If that is your situation, we will tell you rather than string it out.
Working with an Independent Broker – Frequently Asked Questions
Q1. What does it mean that you represent several insurance companies?
It means we are an independent broker rather than a captive agent. A captive agent works for one company and can only offer that company’s products. We hold appointments with a number of carriers, so one set of details from you can be quoted across several of them – and if one declines your risk or raises your rate, we have somewhere else to go.
Q2. Does it cost more to use a broker?
No, and there is no fee to you for the comparison. A broker is compensated by the carrier that ultimately writes the policy, which means the price you pay is the carrier’s price. What you get in addition is somebody who knows which carriers want your type of risk and who stays involved at renewal and at claim time.
Q3. Which insurance companies do you represent?
Mercury Insurance Group, Safeco, Liberty Mutual, Progressive, Kemper, Infinity, Alliance United, Bristol West, Dairyland, Foremost, MAPFRE, Hagerty for classic cars, and Berkshire Hathaway GUARD, among others. Carrier appointments do change over time, so it is always worth asking what is currently available for your situation.
Q4. What is carrier appetite?
Every insurance company decides which risks it wants to write and which it does not – by vehicle type, driver history, property location, business class and a dozen other factors. That is its appetite. It is why a decline from one carrier tells you very little about the rest of the market, and why knowing the appetites is most of a broker’s actual job.
Q5. My insurer non-renewed me. Can you help?
That is one of the main reasons people come to an independent broker, and yes. A non-renewal notice gives you a deadline rather than a solution, and one carrier’s decision does not reflect the whole market. Bring the notice and your current declarations page and we will work through what is available before the date on it.
Q6. Can I switch insurance companies in the middle of a policy?
Yes. You can cancel mid-term and receive a pro-rata refund of the unused premium in most cases – you do not have to wait for renewal. What matters is that the new policy is bound before the old one ends, so there is no gap in coverage. A gap can affect your rate for years afterwards.
Q7. Do you handle both personal and business insurance?
Both. On the personal side: auto including classic and non-standard, home, renters, condo, landlord and flood. On the commercial side: general liability, commercial property, workers’ compensation, commercial auto, and specialist lines including limousine and charter bus. Consolidating several policies onto one panel is usually worth a conversation.
Q8. Do you write classic and collector cars?
Yes – Hagerty is on our panel specifically for that. Classic and collector vehicles are rated very differently from daily drivers, typically on an agreed value basis with mileage and storage conditions attached, and a standard auto policy is usually the wrong product for them.
Q9. What if my situation is unusual?
That is generally when a panel is worth the most. A young driver, a prior claim, a lapse in coverage, a rideshare vehicle, a home in a brush area, a business in a class most carriers avoid – each of those suits a different carrier, and several on our panel exist specifically to write risks the standard market turns away.
Q10. How do I get started?
Call 714-761-4336, email rai@raisinsurance.com, or visit us at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801. If you already have coverage, having your current declarations page to hand makes the conversation much faster – it tells us your limits, deductibles and renewal date in one document.
Talk to Us About Your Options
contact Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or visit 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801.
If you already hold coverage, have your declarations page to hand. It shows your limits, deductibles and renewal date in one document, and it makes the comparison far quicker and far more accurate.