

Auto Insurance San Diego California
Auto insurance for San Diego drivers, quoted across several carriers by Rais Insurance.
Driving is routine enough that it is easy to forget what it involves – a couple of tons of metal moving at speed, in traffic, alongside everybody else doing the same. Claims happen, and they are expensive when they do. Which is why the useful conversation about auto insurance San Diego drivers need – and what the auto insurance San Diego market actually offers – is not just about the quote, but about understanding what you are buying.
The original version of this page makes exactly that point, and then raises something no other page on this site does: the optional extras you can add. It names three of them and stops at “or etc.” This car insurance guide picks that up.
What the Minimum Actually Covers
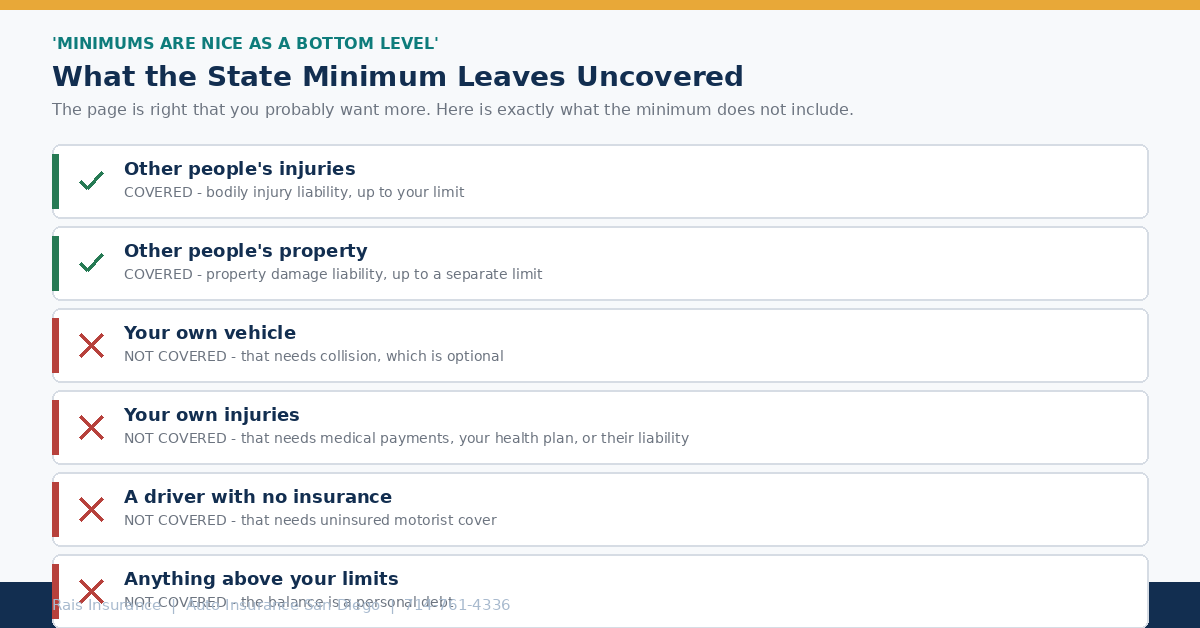
The original is right that state minimums are a floor rather than a target, and right that you should think about your own vehicle and your own injuries as well as other people’s. Here is precisely what that auto insurance floor includes:
- Other people’s injuries– covered, by bodily injury liability, up to your limit.
- Other people’s property– covered, by property damage liability, up to a separate limit. See how liability limits actually work.
- Your own vehicle– not covered. That needs collision, which is optional.
- Your own injuries– not covered. That needs medical payments, your health plan, or the at-fault driver’s liability.
- A driver with no insurance– not covered. That needs uninsured motorist and underinsured motorist cover, optional here and declined in writing.
- Anything above your limits– not covered. The balance of a judgment is a personal debt.
Two things covered and four not. The current minimum figures are on our auto insurance in California page.
The Add-Ons, Named Properly
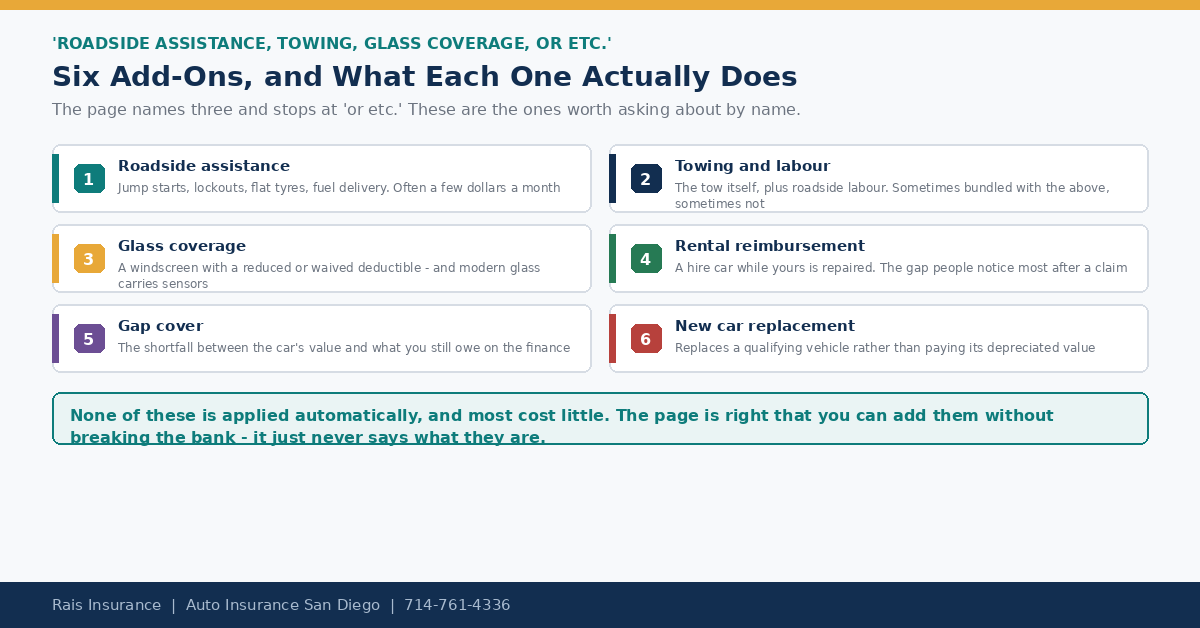
This is the part the original raises and leaves open. “Roadside assistance, towing, glass coverage, or etc.” – the etc. is doing a lot of work there. Six car insurance add-ons worth asking about by name:
- Roadside assistance.Jump starts, lockouts, flat tyres, fuel delivery. Often a few dollars a month, and used more often than most cover.
- Towing and labour.The tow itself plus roadside labour at the scene. Sometimes bundled with roadside assistance and sometimes sold separately – worth checking rather than assuming.
- Glass coverage.A windscreen with a reduced or waived deductible. More valuable than it used to be, for reasons below.
- Rental reimbursement.A hire car while yours is repaired. The one people miss most.
- Gap cover.The shortfall between what the car is worth and what you still owe on the finance – relevant for the first year or two of a loan.
- New car replacement.Replaces a qualifying vehicle rather than paying its depreciated value. Age and mileage limits apply, and not every carrier offers it.
The original’s closing point is right: most of these cost little. What it does not say is that none is applied automatically. The reason drivers do not have them is usually that nobody named them, rather than that they were priced out.
The one people miss most
Nothing else on a standard policy pays for a replacement car.
Rental reimbursement, without question. The gap it fills is immediate and obvious the moment it appears:
- Repairs take longer than expected.Parts availability, sensor recalibration and shop backlogs all add days.
- A total loss takes longer still– valuation and settlement can run to weeks before you can replace the vehicle.
- Nothing else on the policy covers it.Collision repairs your car; it does not put you in another one meanwhile.
- The at-fault driver’s insurer may payif somebody else caused it – but only once they accept responsibility, which takes time you have to fund yourself.
Glass coverage has changed
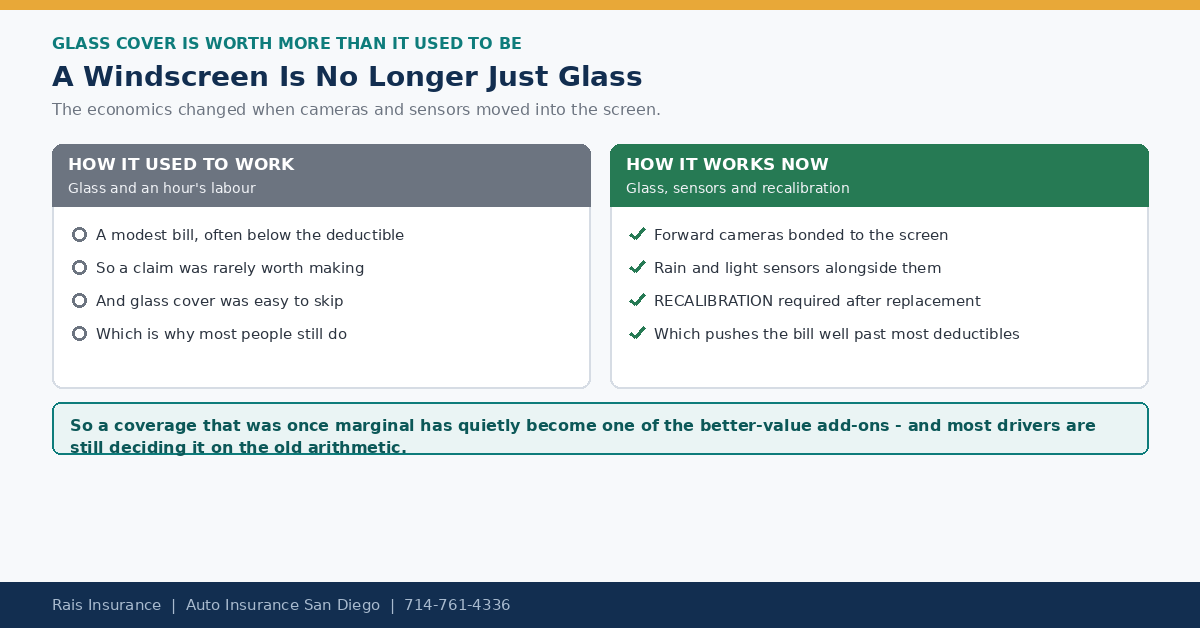
Modern glass carries cameras and sensors, and replacing it means recalibrating them.
This one is worth reconsidering even if you have skipped it before. A windscreen used to be a pane of glass and an hour’s labour – often below the comprehensive deductible, which made the cover marginal.
A modern windscreen is not just glass. Forward-facing cameras are mounted on it, rain and light sensors are bonded to it, and every replacement requires recalibrating them. That pushes the bill well past most deductibles, which changes the arithmetic entirely. See what comprehensive coverage actually covers.
Whether the underlying physical damage coverages still earn their premium on an older vehicle is a separate question: see when collision and comprehensive stop earning their premium.
Driving in San Diego
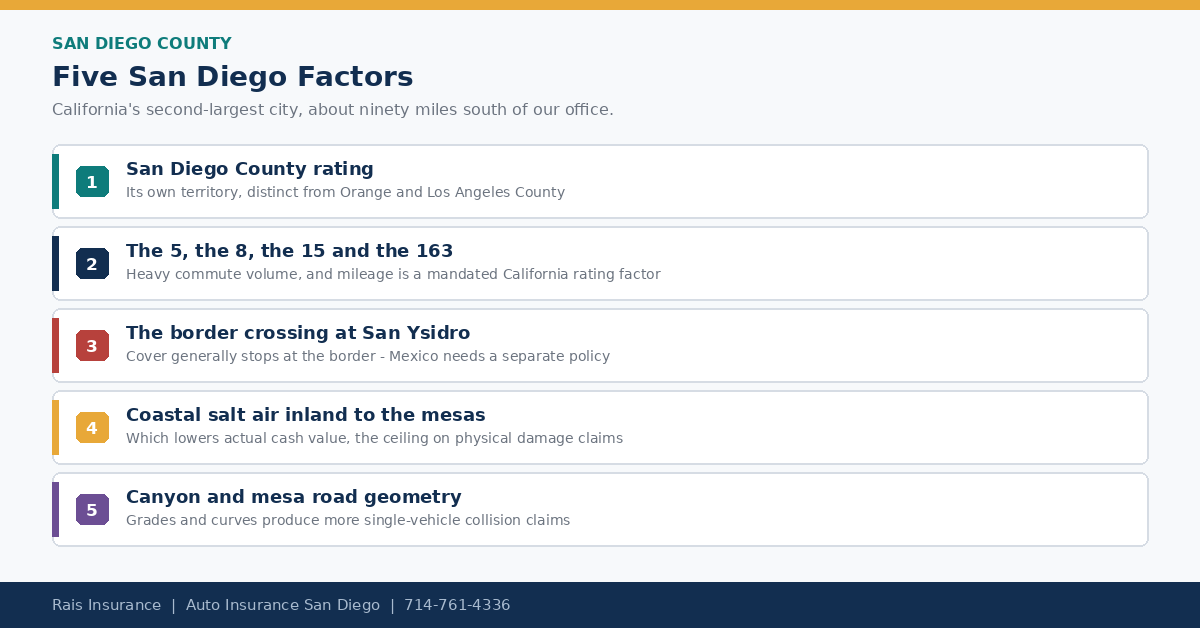
California’s second-largest city, about ninety miles south of our office.
Five things that shape car insurance San Diego rates specifically, on top of the auto insurance San Diego basics above:
- San Diego County rating.Its own territory, distinct from Orange and Los Angeles County – and California rates by garaging territory rather than city name.
- The 5, the 8, the 15 and the 163, and annual mileage is one of the three factors state law requires to weigh most heavily.
- The border crossing at San Ysidro.A US auto policy generally stops at the border – driving into Mexico needs a separate Mexican policy, arranged before the trip rather than at the crossing.
- Salt air from the coast inland to the mesas, which affects vehicle condition and therefore actual cash value – the ceiling on every physical damage claim.
- Canyon and mesa road geometry, where grades and curves produce more single-vehicle collision claims than flat grid driving.
Carlsbad is the other San Diego County page on this site, and it covers a different question – who is covered to drive your car.
Understanding What You Are Getting
The original’s central argument is a good one and worth restating: securing a competitive quote is only half of it. The other half is knowing what the car insurance does when something happens – which coverages you hold, which you declined, and which optional extras would close a gap you have not thought about.
As an independent broker we place business across a panel of carriers rather than selling one company’s products, so one set of details gets quoted several times – see the insurance companies we represent. We are not an insurance company; the carrier issues the policy and pays the claim, and there is no fee to you for the comparison. Our office is in Anaheim, about ninety miles north, so San Diego is served by phone and email.
Auto Insurance in San Diego – Frequently Asked Questions
Which auto insurance add-ons are actually worth it?
Six are worth asking about by name. Roadside assistance and towing are cheap and used often. Rental reimbursement is the one people miss most. Glass coverage is worth more than it used to be. Gap cover matters on a financed vehicle, and new car replacement on a recent one. None is applied automatically – you have to ask for each of them.
What is rental reimbursement?
It pays for a hire car while yours is being repaired after a covered claim, usually with a daily limit and a maximum number of days. Nothing else on a standard policy does this – collision repairs your vehicle, it does not put you in another one meanwhile. It is one of the cheaper endorsements and the gap is felt immediately.
Doesn’t the other driver’s insurer pay for a hire car?
If somebody else caused the accident, their liability may cover it – but only once they have accepted responsibility, which can take weeks. Rental reimbursement on your own policy starts working straight away, which is the practical difference between the two.
Why is glass coverage worth more than it used to be?
Because a modern windscreen is not just glass. Forward-facing cameras are mounted on it, rain and light sensors are bonded to it, and all of that has to be recalibrated after a replacement. A job that once sat below most deductibles now often runs well past them – which changes the arithmetic on an endorsement many drivers used to skip.
What does the state minimum leave uncovered?
Four things. Your own vehicle – that needs collision. Your own injuries – that needs medical payments, your health plan, or the at-fault driver’s liability. A driver with no insurance – that needs uninsured motorist cover. And anything above your limits, which becomes a personal debt. The minimum covers other people’s injuries and property, and nothing else.
What is towing and labour coverage?
It pays for a tow and for roadside labour at the scene. Sometimes it is bundled with roadside assistance and sometimes sold separately, which is worth checking rather than assuming – two policies with the same premium can differ on exactly this point.
Does my policy cover me driving into Mexico?
Generally not. A US auto policy usually stops at the border, and driving in Mexico requires a separate Mexican policy issued by a Mexican carrier. This matters more in San Diego than almost anywhere else in the state, and it is worth arranging before the trip rather than at the crossing.
Do I need uninsured motorist coverage?
It is optional in California and a carrier must obtain your decline in writing. It responds when the at-fault driver has no insurance or not enough of it – the one situation nothing else on your policy answers, since what you recover otherwise depends entirely on their limits.
Are these add-ons expensive?
Mostly not, and the original version of this page is right about that. Roadside assistance and towing typically cost a few dollars a month. Rental reimbursement and glass are modest. Gap cover is inexpensive relative to what it prevents. The reason people do not have them is usually that nobody named them, not that they were priced out.
How do I get a San Diego auto insurance quote?
Call Rais Insurance on 714-761-4336 or email rai@raisinsurance.com. Our office is in Anaheim, about ninety miles north, so San Diego is served by phone and email. We are an independent broker, so one set of details is quoted across several carriers, and there is no fee to you for the comparison.
Get a Car Insurance Quote in San Diego
contact Rais Insurance on 714-761-4336 or email rai@raisinsurance.com.
Worth asking about the auto insurance add-ons even if you are not changing anything else. They are individually cheap, none is applied automatically, and most drivers who do not have them simply were never told they existed.
