
Auto Insurance Carlsbad California
That is a good way to see what the product is for. California is an at-fault state, so the person responsible for a collision is responsible for the cost of it – and auto insurance Carlsbad drivers carry is what stands between that liability and their own assets.
This car insurance guide covers the question that follows from all of that and is rarely answered properly: who is actually covered to drive your car.
Who Is Actually Covered to Drive Your Car
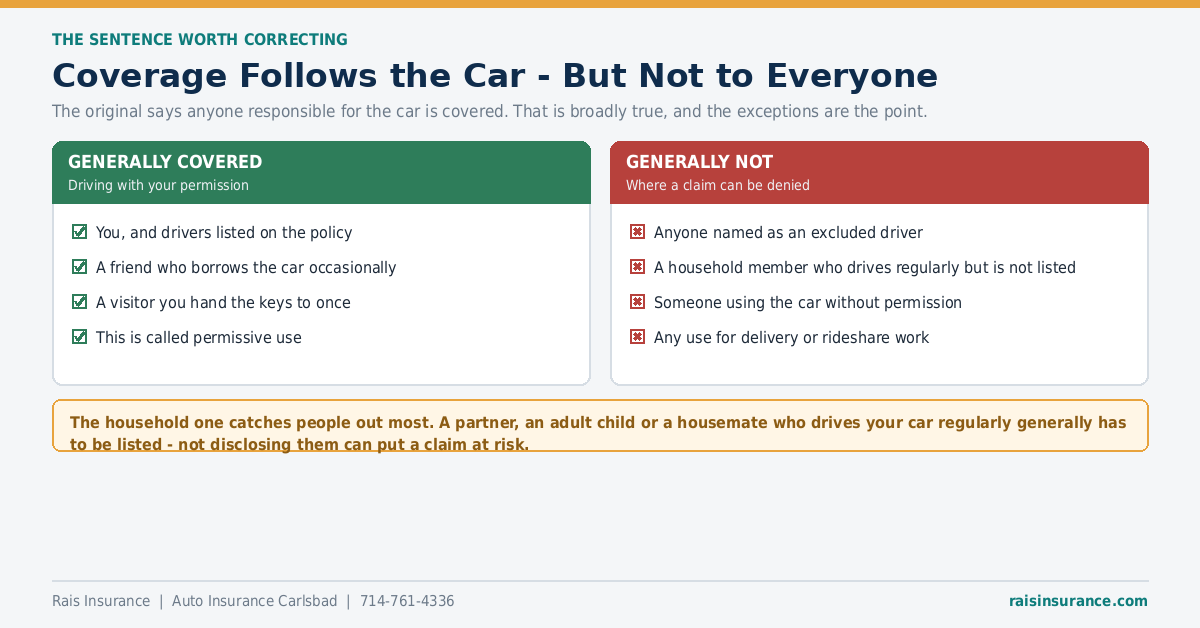
The original version of this page says that coverage is on a per-vehicle basis, meaning anyone responsible for the car at any time is covered. That is broadly the right instinct – coverage follows the car first and the driver second – but the exceptions are where claims are lost, so they are worth stating.
Generally covered:
- You, and any drivers listed on the policy.
- A friend or visitor who borrows the car occasionally with your consent. This is called permissive use, and it is what the original is describing.
Generally not covered:
- Anyone named as an excluded driver. This is a real, binding exclusion – usually added to keep a premium down when a household member has a poor record. If that person drives and crashes, there is no cover at all, not reduced cover.
- A household member who drives regularly but was never added. Carriers expect regular household drivers to be disclosed and rated. This is the one that catches people out most – a partner, an adult child or a housemate using the car routinely generally has to be listed.
- Anyone using the vehicle without your permission.
- Any use for delivery, courier or rideshare work. Personal policies generally exclude driving for compensation. Some carriers offer an endorsement or a specific product, and it is worth resolving before you start rather than after a claim.
The original also says family members who use your vehicle are covered. Occasional use, yes. Regular use by someone in your household needs them on the policy – which is a five-minute call, and considerably cheaper than a declined claim.
One Thing the Original Overstates
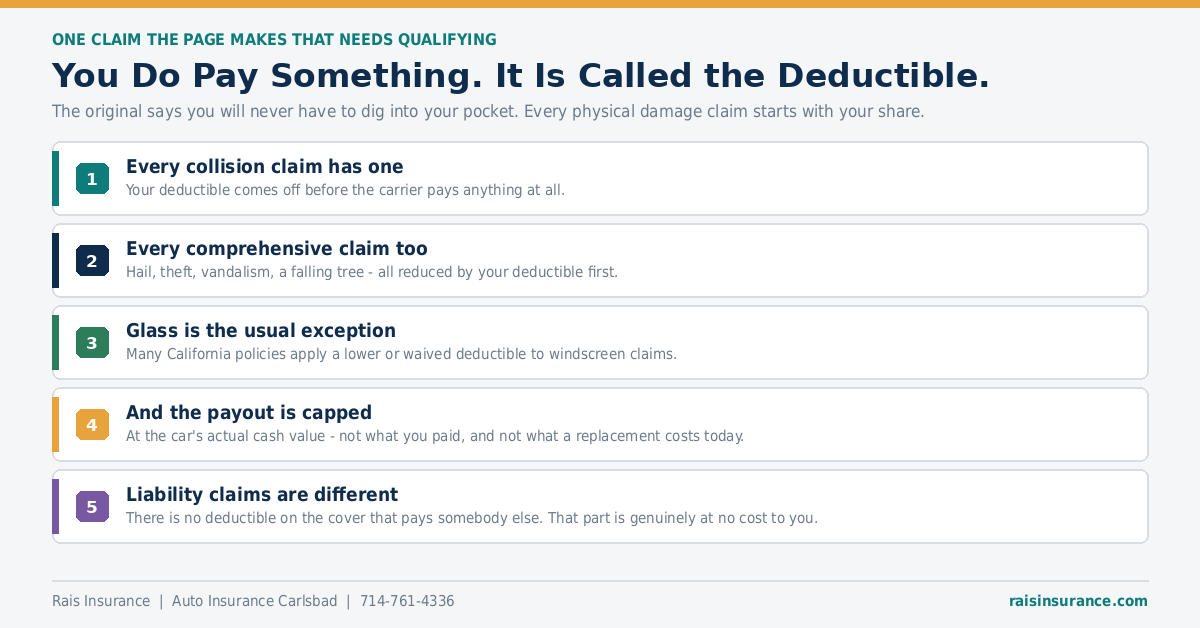
The page says that with insurance you will never have to dig into your pocket. On the liability side that is true – there is no deductible on the cover that pays somebody else. On your own vehicle, it is not:
- Every collision claim is reduced by your deductible before the carrier pays anything.
- Every comprehensive claim too – hail, theft, vandalism, a falling tree. All of it starts with your share.
- Glass is the usual exception. Many California policies apply a lower or waived deductible to windscreen claims.
- And the payout is capped at the car’s actual cash value, not what you paid and not what a replacement costs today.
None of that undermines the argument – it just makes it accurate. The choice of deductible is itself a lever worth thinking about: see when collision and comprehensive stop earning their premium.
What Auto Insurance Actually Protects
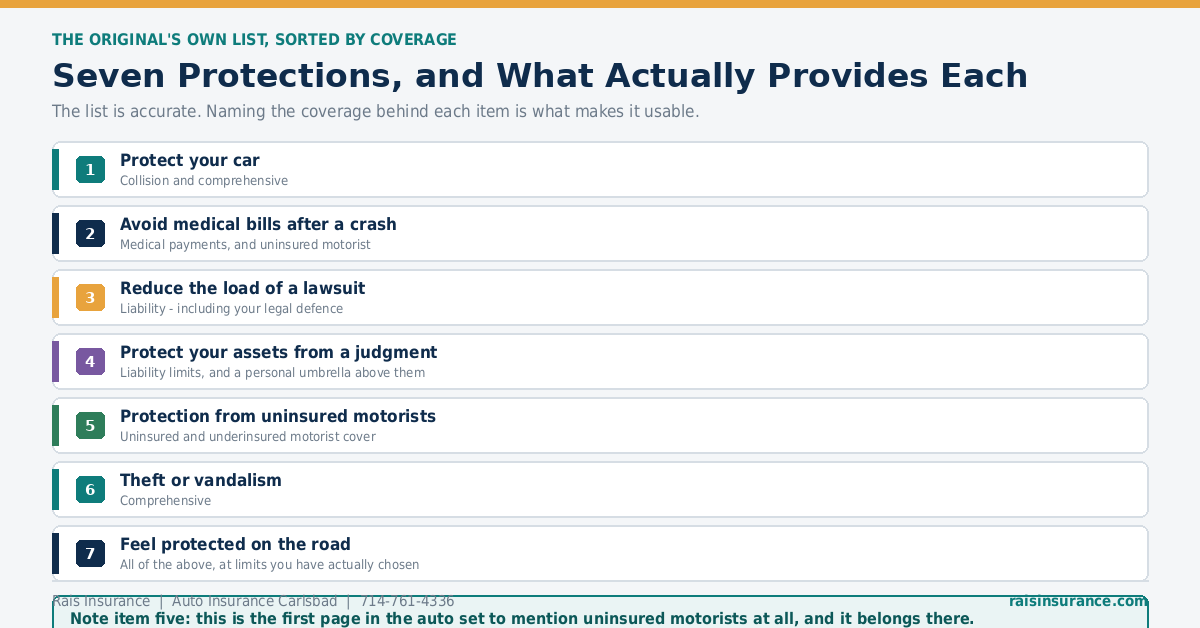
The original lists seven things a car insurance policy does for you. The list is accurate – what it needs is the name of the coverage behind each one, because that is what you actually buy:
- Protect your car – collision and comprehensive.
- Avoid medical bills after a crash – medical payments, and uninsured motorist cover if the other driver has none.
- Reduce the load of a lawsuit – liability, which also funds your legal defence.
- Protect your assets from a judgment – your liability limits, and a personal umbrella above them. See how liability limits actually work.
- Protection from uninsured motorists – uninsured and underinsured motorist cover, which is optional in California and must be declined in writing.
- Theft or vandalism – comprehensive, which also answers the hail and storm damage the page mentions. See what comprehensive coverage actually covers.
- Feel protected on the road – all of the above, at limits you have actually chosen rather than inherited.
Credit where it is due on the fifth item: this is the first page in our auto set to name uninsured motorist cover, and it belongs on any California list. Because what you recover depends on the at-fault driver’s limits, a driver with nothing leaves you nothing to claim against.
Lending, Borrowing and Renting
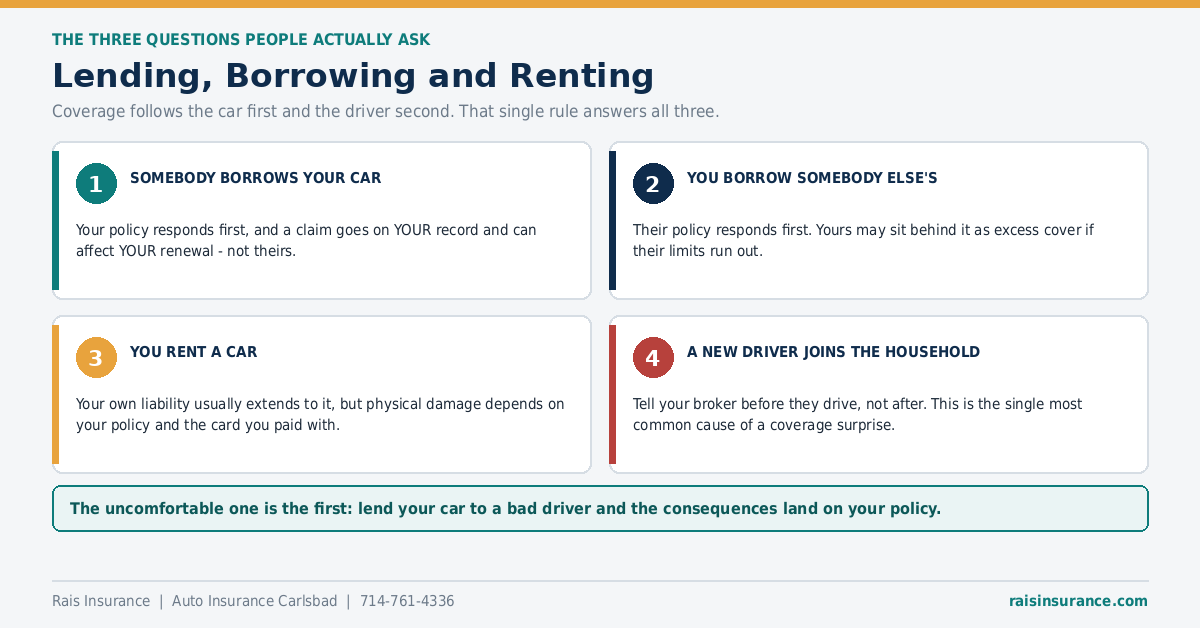
Four situations, all answered by the same car insurance rule – coverage follows the car first:
- Somebody borrows your car. Your auto insurance responds, and the claim goes on your record and can affect your renewal – not theirs. That is the uncomfortable one, and it is worth knowing before you hand over keys.
- You borrow somebody else’s. Their policy responds first; yours may sit behind it as excess cover if their limits run out.
- You rent a car. Your liability usually extends to it, and your collision and comprehensive often do too, subject to your deductible. Some credit cards add secondary cover. Check both before buying the counter waiver – you may already hold it.
- A new driver joins the household. Tell your broker before they start driving. This is the single most common cause of a coverage surprise, and it is entirely avoidable.
Driving in Carlsbad
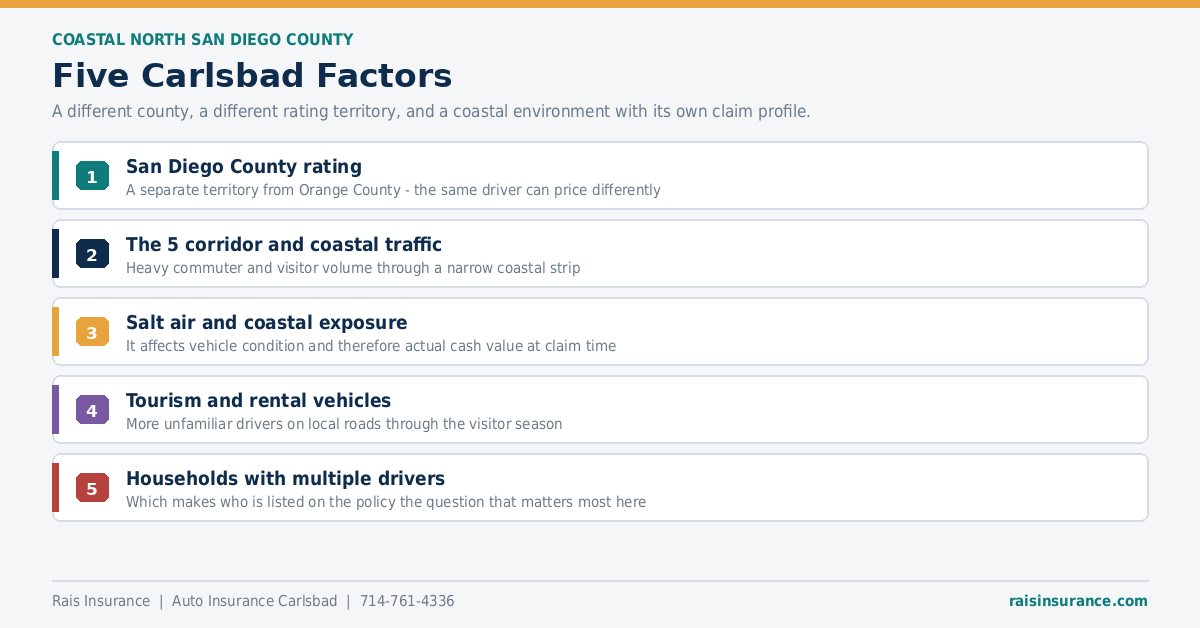
Five things shaping auto insurance Carlsbad rates in this part of the state:
- San Diego County rating. Carlsbad is not in Orange County, and California rates by territory – so the same driver and vehicle can price differently here.
- The 5 corridor and coastal traffic. Heavy commuter and visitor volume through a narrow coastal strip.
- Salt air and coastal exposure. It affects vehicle condition over time, which affects actual cash value at claim time.
- Tourism and rental vehicles. More unfamiliar drivers on local roads through the visitor season.
- Multi-driver households. Which brings this page back to where it started: who is on the policy is the question that matters most.
What sets a California premium generally – and the three factors state law prohibits – is covered on our what determines your premium in California page.
Working With Rais Insurance
We are a family-run independent broker, which means two things worth being clear about. We are not an insurance company – the carrier issues the policy and pays the claim, and we place the business. And because we hold appointments with a number of carriers, one set of details from you gets quoted across several rather than one. See the insurance companies we represent.
Being straightforward about geography: our office is in Anaheim, so car insurance Carlsbad households buy through us is arranged by phone and email rather than across a desk. That works well for most people and it is worth saying plainly rather than implying a local branch.
The full coverage list and California’s minimum requirements sit on our auto insurance in California page.
Auto Insurance in Carlsbad – Frequently Asked Questions
Q1. Does my insurance cover someone else driving my car?
Usually yes, under what is called permissive use – a friend or visitor who borrows the car occasionally with your consent is generally covered. The important exceptions are anyone named as an excluded driver, a household member who drives regularly but was never added to the policy, and anyone using the vehicle without your permission.
Q2. Does insurance follow the car or the driver?
The car first, the driver second. Your policy responds when someone borrows your vehicle, and their own policy may sit behind yours as excess cover if your limits are exhausted. That single rule answers most lending questions – including the uncomfortable one, which is that a claim lands on your record and can affect your renewal rather than theirs.
Q3. Do I need to add my spouse or adult child to the policy?
If they live in your household and drive the vehicle with any regularity, generally yes. Carriers expect regular household drivers to be disclosed and rated, and not disclosing one can put a claim at risk. It is worth telling your broker before a new driver starts using the car rather than after something happens.
Q4. What is an excluded driver?
Someone specifically named on the policy as not covered – usually added to keep a premium down when a household member has a poor record. It is a real and binding exclusion: if that person drives the car and has an accident, there is no coverage at all, not reduced coverage. Worth checking whether anyone is listed this way on your own policy.
Q5. Am I covered driving somebody else’s car?
Generally yes, with their permission – their policy responds first and yours may follow as excess. The exceptions are much the same: if you are an excluded driver on their policy, or if you live in their household and were never listed, coverage can fail. Borrowing a car regularly is a reason to be added to it.
Q6. Does my car insurance cover a rental car?
Your liability coverage usually extends to a rental in the United States, and if you carry collision and comprehensive, those often extend as well – subject to your own deductible. Some credit cards add secondary cover for physical damage. Confirm both before you buy the counter waiver, because you may be paying for something you already hold.
Q7. Am I covered for delivery or rideshare driving?
Generally not on a personal auto policy. Most policies exclude driving for compensation, which includes food delivery, courier work and rideshare. Some carriers offer an endorsement or a specific rideshare product. This is one of the more common gaps to appear in recent years, and it is worth resolving before you start rather than after a claim.
Q8. Do I pay a deductible if the accident was not my fault?
It depends which coverage responds. If you claim on the at-fault driver’s liability coverage, you pay nothing. If you claim on your own collision cover – because they were uninsured, or to get repairs started sooner – your deductible applies, though it may be reimbursed later if your carrier recovers from theirs.
Q9. Does insurance cover hail or storm damage to my car?
Yes, under comprehensive coverage, which the original version of this page refers to correctly. Hail, wind, falling branches, flood and fire all sit there. It is optional cover, it carries its own deductible, and the payout is capped at the vehicle’s actual cash value.
Q10. How do I get a Carlsbad auto insurance quote?
Call Rais Insurance on 714-761-4336 or email rai@raisinsurance.com. Our office is in Anaheim, and we place business across San Diego County remotely – so this is a phone and email relationship rather than a walk-in one. Have your declarations page to hand, and a list of everyone in the household who drives the vehicle.
Get a Car Insurance Quote in Carlsbad
contact Rais Insurance on 714-761-4336 or email rai@raisinsurance.com.
Two things to have ready for a car insurance Carlsbad quote: your declarations page, and a list of everyone in the household who drives the vehicle. The second one is the question most quotes get wrong, and it is the one most likely to matter at claim time.