
Auto Insurance Elk Grove California
Auto insurance for Elk Grove drivers, quoted across several carriers by Rais Insurance.What happens if you pull out and hit another vehicle? If you damage their car, or injure the people in it? Those are the right questions to ask before you need the answers – because without adequate cover, the bill comes out of your property and your savings.
Every auto insurance elk grove quote we prepare starts by checking exactly this — who’s actually covered before the accident happens.
Auto insurance Elk Grove drivers carry answers most of that, and good auto insurance answers it well. But there is a subtlety worth getting straight, and the original version of this page gets closer to it than most: whose injuries does each part of the policy actually pay for? The answer covers more people than you might expect, and excludes exactly one.
Whose Injuries Does Your Policy Pay For?
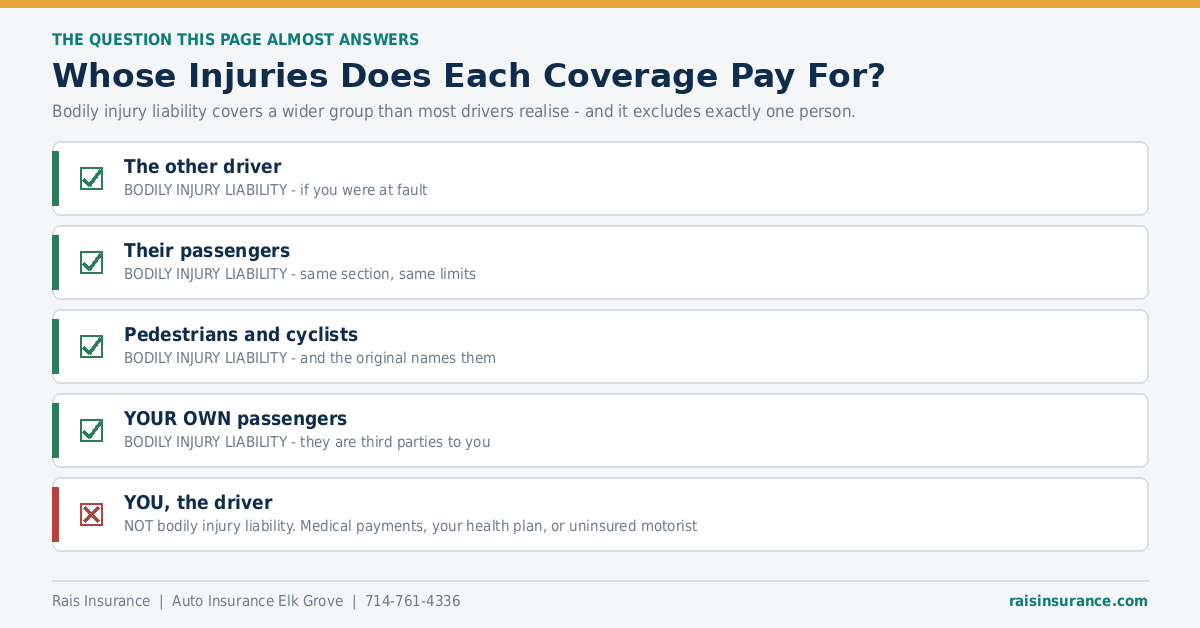
Bodily injury liability pays medical treatment, rehabilitation and funeral costs where you were at fault. This part of your car insurance covers a wider group than most drivers realise, and the original names them correctly:
- The other driver – the obvious one.
- Their passengers – same section, same limits.
- Pedestrians and cyclists – named in the original, and often left out elsewhere.
- Your own passengers. This is the one people are surprised by. Your passengers are third parties to *you*, so if you caused the accident, your own bodily injury liability covers their injuries.
Property damage liability is the companion coverage – repair or replacement of cars and property belonging to other people. Both are required in California; how the limits on them work is set out on our how liability limits actually work page.
The One Person Liability Does Not Cover
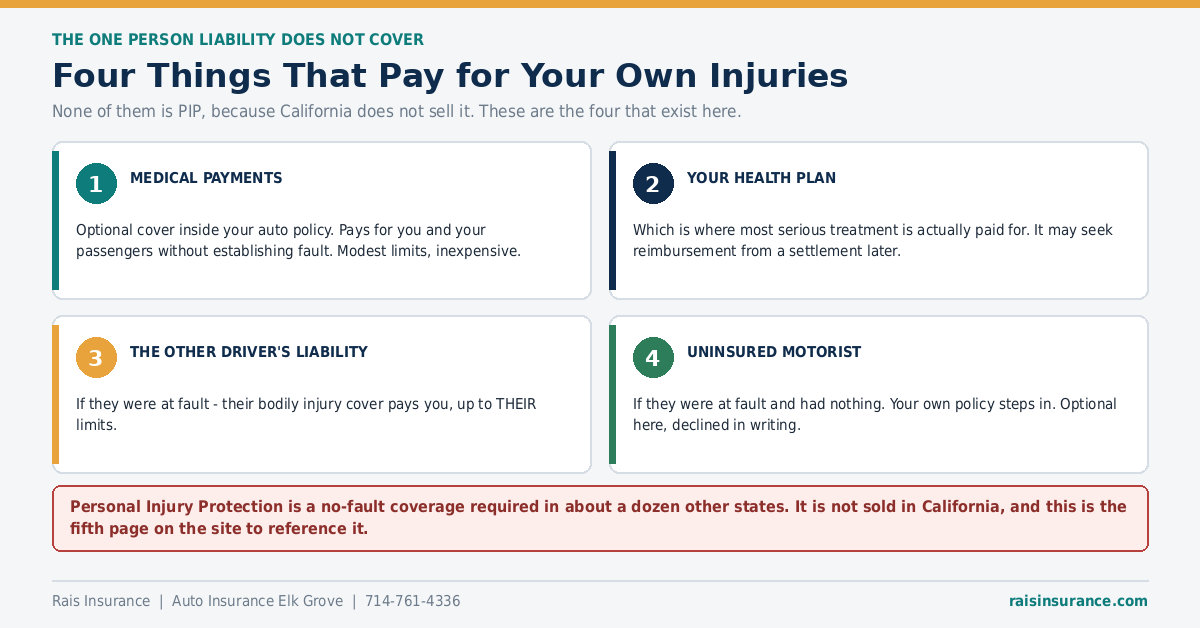
You. That coverage pays everybody else in the list above and not the driver who bought it. The original gestures at this and then contradicts itself – it says bodily injury liability “won’t provide coverage for injury”, which is not quite right. It covers injury; it just does not cover your injury.
It then suggests personal injury protection (PIP) as the answer to that gap. That needs correcting: PIP is not sold in California. It is a no-fault coverage required in about a dozen other states, where your own policy pays your injury costs regardless of blame. California is an at-fault state – see California is an at-fault state.
Four things do pay for your own injuries here:
- Medical payments coverage. Optional, inside your auto policy, and it pays for you and your passengers without anyone establishing fault first – which is the useful part, because treatment starts while the fault argument is still running. Modest limits, inexpensive.
- Your health plan, which is where most serious treatment is actually paid for. Note it may seek reimbursement from a settlement later.
- The other driver’s liability cover, if they were at fault – up to *their* limits.
- Your own uninsured motorist cover, if they were at fault and had no insurance. It is optional in California and a carrier must obtain your decline in writing.
That last one is missing from the original auto insurance list entirely, and it is the most consequential omission – in an at-fault state, a driver with nothing leaves you nothing to claim against.
The Coverages, Checked
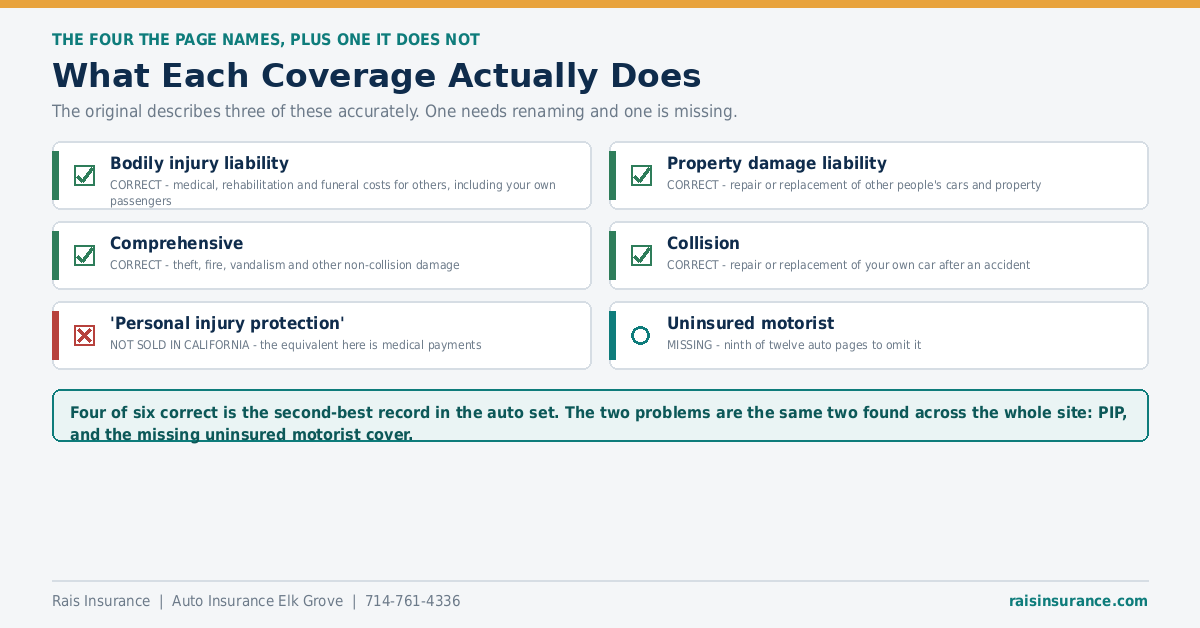
The rest of the original’s auto insurance descriptions are sound and are kept close to as written:
- Comprehensive – for the things that are not collisions. As the page puts it, your vehicle is not only vulnerable to accidents: it can be stolen, damaged by fire, or vandalised. See what comprehensive coverage actually covers.
- Collision – repair or replacement of your own car when it is involved in an accident, regardless of fault and subject to your deductible.
Both are optional, both carry their own deductible, and a lender will usually require both while a vehicle is financed. The current minimum requirements are on our auto insurance in California page.
On vehicle types, the original is right that the answer differs by car. A classic or collector vehicle is generally the wrong fit for a standard policy – those are written on an agreed value basis with mileage and storage conditions attached. See classic car insurance. A luxury vehicle changes the collision and comprehensive calculation too, simply because the amount at risk is larger.
Driving in Elk Grove
Five things shaping car insurance Elk Grove rates in this part of California:
- Sacramento County rating. A completely separate territory from Southern California, and rates differ materially between them.
- Highway 99 and Interstate 5. Long commutes into Sacramento, and annual mileage is one of the factors California law requires to weigh most heavily.
- Winter tule fog. A genuine Central Valley hazard and a real multi-vehicle collision risk – which is a practical argument for carrying collision rather than liability alone.
- Flood plain and levee proximity. Comprehensive answers flood damage to a vehicle, which is worth knowing in the Delta region.
- We serve Elk Grove remotely. Our office is in Anaheim, so this is a phone and email relationship rather than a walk-in one – worth saying plainly rather than implying a local branch.
Getting the Cover Right
We will help you work out which car insurance coverages your situation calls for, whether that is a luxury car, a classic, or the family sedan doing the school run and the commute.
One clarification the original blurs: Rais Insurance is an independent broker, not an insurance company. The carrier issues the policy and pays the claim; we place the business across a panel of carriers, which means one set of details from you gets quoted several times rather than once. See the insurance companies we represent. There is no fee to you for the comparison.
We also place home and flood insurance, so if you are consolidating policies it is worth mentioning – bundling is usually the largest single discount available.
Auto Insurance in Elk Grove – Frequently Asked Questions
Q1. Does my liability insurance cover my own passengers?
Yes. Your passengers are third parties to you, so if you are at fault their injuries fall under your bodily injury liability coverage – the same section and the same limits that cover the other driver. The original version of this page states this correctly, which is worth noting because it is a point a lot of insurance writing gets wrong.
Q2. Does bodily injury liability cover my own injuries?
No, and this is the one exception. Bodily injury liability covers everyone else – the other driver, their passengers, pedestrians, cyclists and your own passengers – but not you. For your own injuries you are looking at medical payments cover, your health plan, the other driver’s liability if they were at fault, or your own uninsured motorist cover if they had none.
Q3. Is personal injury protection available in California?
No. PIP is a no-fault coverage required in about a dozen other states, where your own policy pays your injury costs regardless of blame. California is an at-fault state and does not use PIP. The nearest equivalent sold here is medical payments coverage, which is optional, carries modest limits, and works differently.
Q4. What is medical payments coverage?
An optional coverage inside your auto policy that pays medical costs for you and your passengers without anyone having to establish fault first. That is the useful part – treatment starts while the fault argument is still running. The limits are modest and it is inexpensive, and it does not replace a health plan.
Q5. Who pays my medical bills after a car accident?
It depends on fault. If the other driver caused it, their bodily injury liability pays you, up to their limits. If they had no insurance, your own uninsured motorist cover responds. Meanwhile your medical payments cover and your health plan can start paying immediately, which matters because liability claims take time to settle.
Q6. Does bodily injury liability cover funeral costs?
Yes. The original version of this page names medical treatment, rehabilitation and funeral costs, and all three fall under bodily injury liability where you were at fault. It also covers pedestrians and cyclists, which is a detail many pages leave out.
Q7. What does comprehensive cover that collision does not?
Comprehensive answers damage that is not a collision – theft, fire, vandalism, weather, falling objects and animal strikes. Collision repairs your own vehicle after hitting something, regardless of fault. Both are optional, both carry their own deductible, and a lender will usually require both while a car is financed.
Q8. Do I need uninsured motorist coverage?
It is optional in California and a carrier must obtain your decline in writing. It matters because California is an at-fault state – what you recover depends on the other driver’s limits, so a driver with no coverage leaves you nothing to claim against. This is the coverage that fills that gap, and it was missing from the original version of this page.
Q9. Do you cover classic and luxury vehicles?
Yes. A classic or collector vehicle is generally the wrong fit for a standard policy – those are written on an agreed value basis with mileage and storage conditions attached. Luxury and higher-value vehicles also change the collision and comprehensive calculation, because the amount at risk is larger. That’s the fastest way to get an auto insurance elk grove quote built around your actual coverage needs.
Q10. Are you based in Elk Grove?
No – our office is at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801, and we place business across California. Elk Grove is served by phone and email rather than across a desk. Call 714-761-4336 or email rai@raisinsurance.com and have your declarations page to hand. That’s the fastest way to get an auto insurance elk grove quote built around your actual coverage needs.
Get a Car Insurance Quote in Elk Grove
For car insurance Elk Grove quotes, contact Rais Insurance on 714-761-4336 or email rai@raisinsurance.com. We’re happy to walk through your car insurance elk grove options over the phone before you commit to anything.
Have your declarations page to hand. Two lines are worth checking first: whether you carry medical payments cover, and whether you carry uninsured motorist. Both are optional, both pay for your injuries rather than somebody else’s, and both are commonly declined without the driver realising it. Ask us for car insurance elk grove ca quotes that spell out exactly which of these coverages you’re carrying.