
Auto Insurance Anaheim California
Auto insurance for Anaheim drivers, from a broker with an office on West Lincoln Avenue.Areas we serve: 92801 | 92802 | 92803 | 92804 | 92805 | 92806 | 92807 | 92808 | 92809 | 92812 | 92814 | 92815 | 92816 | 92817 | 92825 | 92850 | 92899
Owning a vehicle gives you a kind of freedom almost nothing else does. Driving it uninsured can undo that very quickly – and in California the consequences of an accident fall on whoever caused it, which makes the cover you carry more consequential here than in a good many other states. We’ve placed anaheim auto insurance for local drivers of every kind, from first policies to fleet renewals.
Rais Insurance is an independent broker on West Lincoln Avenue in Anaheim. This is the city we actually work from, not one we serve at a distance – which means auto insurance Anaheim drivers buy from us can be arranged over the phone or across a desk, whichever you prefer. Rais Insurance Anaheim clients deal with the same person from quote through renewal, not a rotating call centre.
One Correction: California Is Not a No-Fault State
The previous version of this page offered “no-fault insurance” among its products. That is worth correcting plainly, because it describes something that does not exist here.
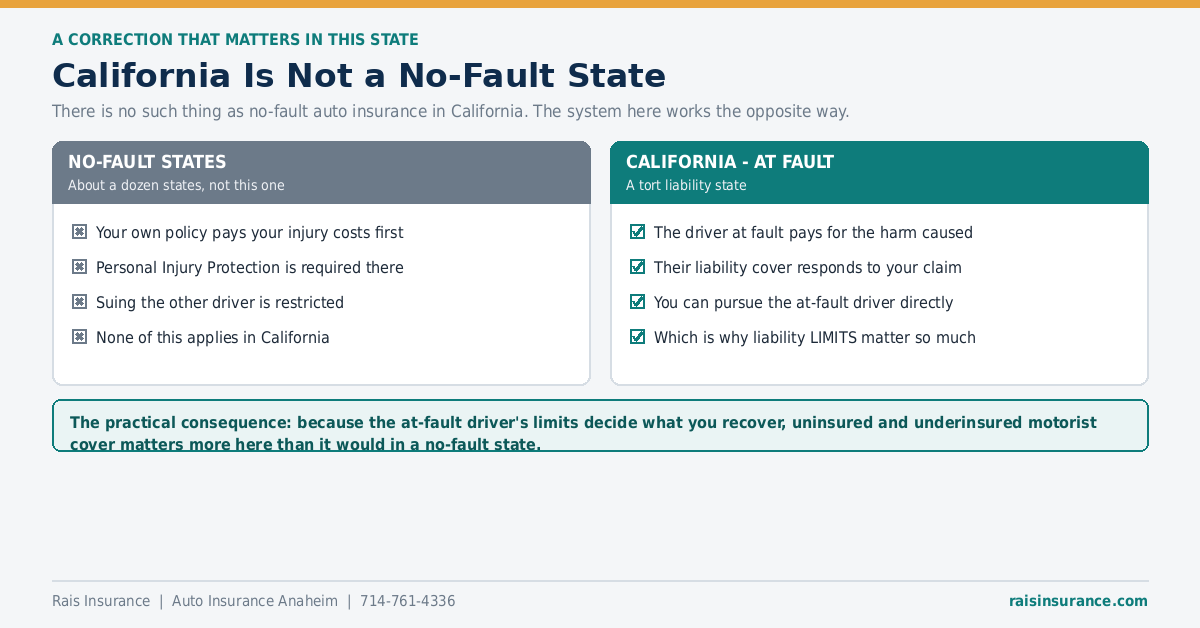
California is an at-fault state – sometimes called a tort liability state. The driver responsible for an accident is responsible for the harm caused, and their liability coverage is what responds. About a dozen states operate no-fault systems, where your own policy pays your injury costs regardless of blame and Personal Injury Protection is required. California is not one of them, and PIP is not sold here.
That distinction has a practical consequence worth understanding. Because what you recover depends on the at-fault driver’s limits, uninsured motorist and underinsured motorist coverage matters more in California than most people assume – if the other driver has nothing, or not enough, your own uninsured motorist cover is the only thing standing between you and the bill. This is exactly why anaheim car insurance shoppers should never skip uninsured motorist coverage, even when it looks optional.
The state minimum limits, the full list of coverages and the penalties for driving uninsured are all covered on our main auto insurance in California page.
Why Options Matter
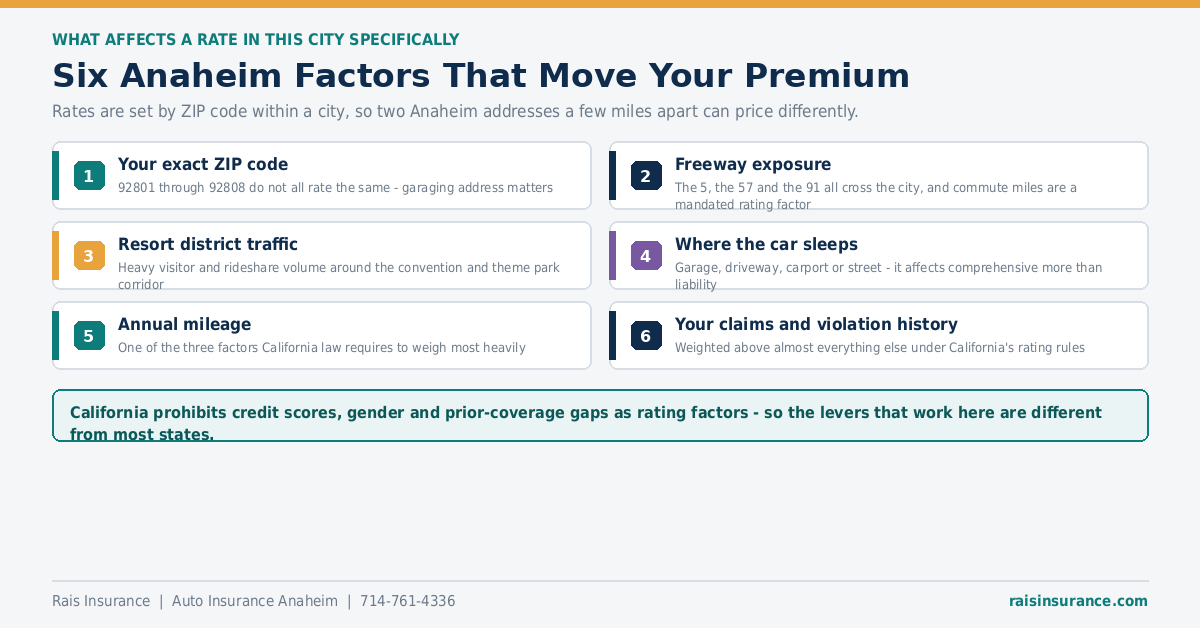
The comparison the original page made is a good one and it is worth keeping. Imagine a grocery store that stocked only one brand of each product. You could still shop there – you simply could not choose. Without options, you cannot find the thing that actually fits.
That is the difference between a captive agent and an independent insurance broker Anaheim drivers can actually use. A captive agent represents one company: one set of rates, one appetite, and if that carrier declines you or raises your rate, the conversation ends. We hold appointments with a number of carriers, so one application from you gets quoted across several – see the insurance companies we represent and our authorized Mercury Insurance agent page. It’s also why working with car insurance agents in Anaheim, CA who hold multiple appointments beats calling one company directly.
There is no fee to you for that comparison. A broker is compensated by the carrier that ultimately writes the policy, so the price you pay is the carrier’s price – you are simply not doing the shopping yourself.
What Moves a Rate in Anaheim Specifically
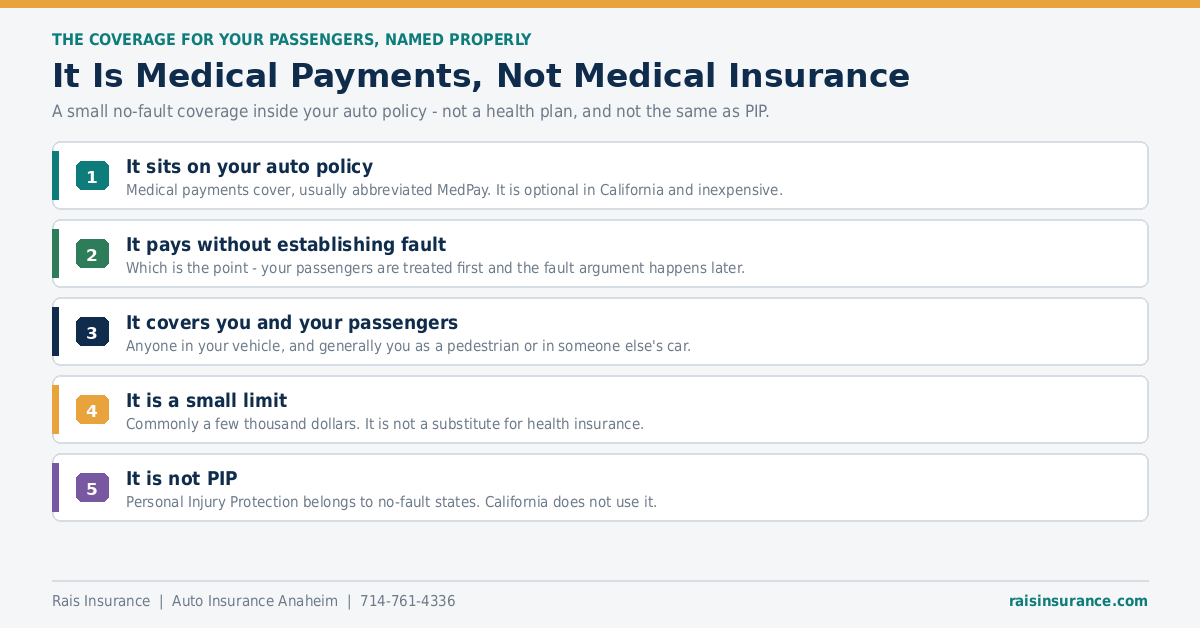
Car insurance Anaheim rates are set by garaging territory rather than by city, so two addresses a few miles apart can price differently. Six things matter here:
- Your exact ZIP code. 92801 through 92808 do not all rate identically. The address on the policy should be where the vehicle actually sleeps.
- Freeway exposure. The 5, the 57 and the 91 all cross the city, and commute mileage is one of the factors California law requires to weigh most heavily.
- Resort district traffic. The convention centre and theme park corridor carries heavy visitor and rideshare volume, which shows up in claims frequency.
- Where the car is kept. Garage, driveway, carport or street – this affects comprehensive cover more than liability.
- Annual mileage. A mandated rating factor in California, and an out-of-date figure from an old commute costs you money every year until it is corrected.
- Your driving record. Weighted above almost everything else under California’s rating rules.
Auto insurance Anaheim Hills addresses often price differently again, since that hillside garaging territory rates separately from the flatland ZIP codes below.
Comparing across carriers is still the most reliable way to find cheap car insurance Anaheim drivers can actually qualify for, rather than assuming one quote is the market.
California also prohibits three factors most states allow: credit-based insurance scores, gender, and penalising a gap in prior coverage. That makes the levers that work here genuinely different, and it is worth knowing before you accept that a rate cannot be improved. These rules are part of what makes anaheim car insurance pricing fairer than in states that still weigh credit scores heavily.
Cover for Your Passengers
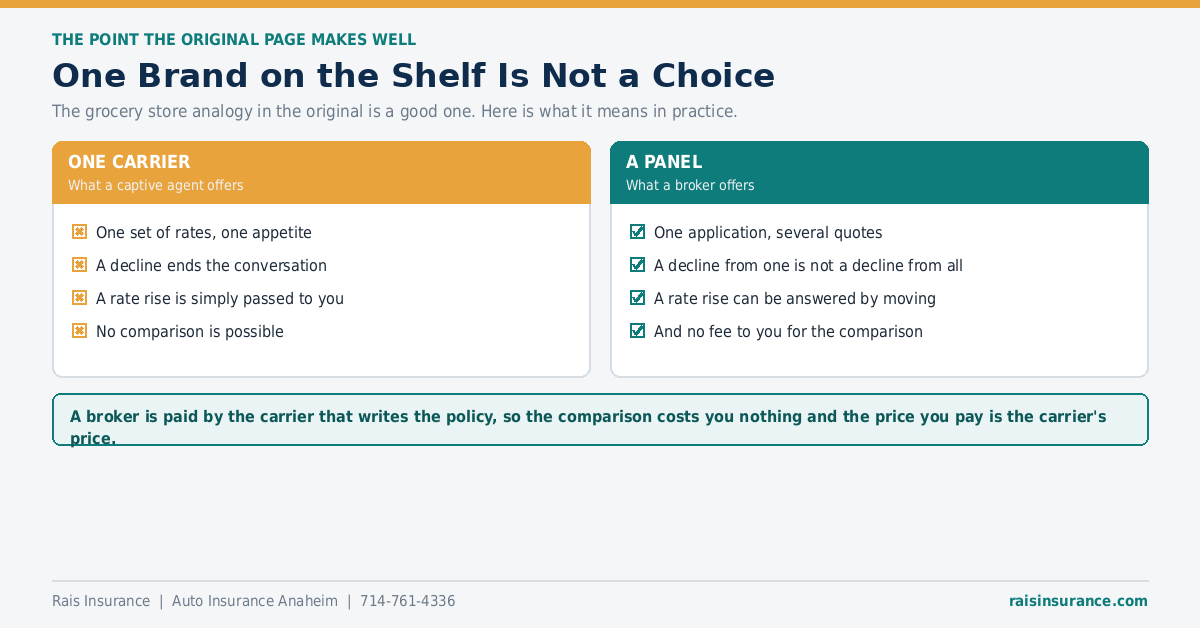
The original page mentions choosing “medical insurance to cover any injuries to your passengers”. The instinct is right and the coverage exists – it is just called something else.
Medical payments coverage, usually shortened to MedPay, sits inside your auto policy. It pays medical costs for you and anyone riding with you without anybody having to establish fault first, which is exactly why it is useful: your passengers are treated while the fault argument happens separately. It is optional in California, the limit is modest, and it is inexpensive relative to what it does.
Two clarifications. It is not medical insurance and it does not replace a health plan. And it is not PIP – that belongs to no-fault states, as above.
Alongside it, the policy can cover damage, theft and vandalism through collision and comprehensive. For a classic or collector vehicle a standard policy is usually the wrong product – see classic car insurance. That’s the kind of detail that separates a solid auto insurance Anaheim policy from a bare-minimum one.
Come and See Us
Most car insurance shopping now happens through a form. That works fine for a straightforward renewal – it works less well when your situation is not standard, when you have been declined, or when you are not sure what you are being asked.
We are at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801, and you are welcome to come in. Bring your current declarations page, your licence details and your vehicle VINs, and we can work through the options while you are here. We write auto insurance Anaheim residents need for both everyday commuting and weekend trips alike.
We also write car insurance Anaheim households need alongside home, renters and business cover – see home insurance in California and, for local businesses, commercial building insurance in Anaheim. Bundling is usually the largest single discount available. Combining home and auto insurance in Anaheim under one carrier is usually where that discount shows up most.
Auto Insurance in Anaheim – Frequently Asked Questions
Q1. Is California a no-fault state for car insurance?
No. California is an at-fault, or tort liability, state – the driver responsible for an accident is responsible for the resulting costs, and their liability coverage responds. No-fault systems, where your own policy pays your injury costs regardless of blame, exist in about a dozen other states. There is no such thing as no-fault auto insurance in California.
Q2. So what is PIP, and do I need it in California?
Personal Injury Protection is the coverage that no-fault states require. California does not use it. The nearest equivalent available here is medical payments coverage, which is optional, considerably smaller, and works differently. If a quote offers you PIP for a California vehicle, that is worth questioning.
Q3. Does my car insurance cover my passengers?
For their injuries, medical payments coverage is what responds – it pays medical costs for you and anyone in your vehicle without anybody having to establish fault first. It is optional in California, the limits are modest, and it is inexpensive. It is not medical insurance and it is not a substitute for a health plan.
Q4. Who pays after an accident in Anaheim?
Whoever is at fault, through their liability coverage. If the other driver caused it, you claim against their policy. If they have no insurance, or not enough of it, your own uninsured or underinsured motorist coverage is what responds – which is why that coverage matters more in an at-fault state than people generally assume.
Q5. Why do rates differ between Anaheim ZIP codes?
California allows rating by garaging territory, so where the vehicle is kept overnight affects the price. Anaheim spans several ZIP codes and they do not all rate identically. It is also why the address on your policy should be where the car actually sleeps – an out-of-date garaging address can cause problems at claim time. This is the same reason auto insurance Anaheim Hills quotes can differ from a quote on a flatland Anaheim ZIP just a few miles away.
Q6. What can and cannot be used to rate me in California?
California requires that your driving safety record, annual miles driven and years of driving experience weigh most heavily, with every other factor weighing less. It prohibits the use of credit-based insurance scores, gender, and penalising a gap in prior coverage. That makes the levers here genuinely different from most states.
Q7. Do you charge a fee to compare quotes?
No. We are an independent broker, compensated by the carrier that ultimately writes the policy, so the price you pay is the carrier’s price. What you get in addition is one application quoted across several carriers, and somebody who knows which of them wants your particular situation. That’s the core difference between us and single-carrier car insurance agents in Anaheim, CA.
Q8. Can I visit your office in Anaheim?
Yes – we are at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801, and Anaheim is the city we actually operate from rather than simply serve. Bring your current declarations page, your licence details and your vehicle VINs and we can work through options while you are here. That in-person option is something Rais Insurance Anaheim customers use more than you’d expect.
Q9. What are the minimum coverage requirements in California?
The state minimum rose on 1 January 2025 to $30,000 bodily injury per person, $60,000 per accident and $15,000 property damage – written as 30/60/15. It replaced the long-standing 15/30/5 minimum. Our main auto insurance page covers the limits, the coverages and the penalties for driving uninsured in full.
Q10. How do I get an Anaheim auto insurance quote?
Call 714-761-4336, email rai@raisinsurance.com, or come to the office on West Lincoln Avenue. Having your current declarations page to hand makes it much faster – it shows your limits, deductibles and renewal date in one document, which is what we need to compare properly rather than approximately. It’s the fastest way to get an anaheim auto insurance quote without guesswork on either side.
Get an Auto Insurance Quote in Anaheim
contact Rais Insurance on 714-761-4336, email rai@raisinsurance.com, or call in at 2612 W. Lincoln Avenue, Suite 103, Anaheim, CA 92801. Rais Insurance Anaheim has been placing local policies from this same West Lincoln Avenue office for years.
If you already hold a policy, bring or send the declarations page. Two lines are worth checking before anything else: your liability limits, and whether you carry uninsured motorist cover at all.
Whatever shape your anaheim auto insurance needs take — from a first policy to home and auto insurance in Anaheim bundled together — bring the details and we’ll quote it properly. Ask us too if you’re hunting for cheap car insurance Anaheim options; we’ll tell you honestly if a lower quote means less coverage, and we regularly quote auto insurance Anaheim Hills residents alongside standard Anaheim ZIPs since that hillside territory rates differently.