
Commercial building insurance Cypress
Protect your commercial building, furniture, tools, inventory and personal property with commercial property insurance Cypress from Rais Insurance. Most Cypress businesses already hold a base commercial building insurance policy. What they usually do not hold are the four extensions that decide whether a claim actually puts the business back together: business personal property, electronic data processing, business interruption and flood. Send us your declarations page and we will tell you which of the four you are missing — free, whether or not you buy from us. Call 714-761-4336.
Commercial Property Insurance Cypress — What the Base Policy Covers
A commercial property insurance policy covers anything from buildings and equipment to inventory and tools. Examples of losses that are typically covered by this type of policy are fires, burglaries, storms, vandalism and other natural disasters. The type of coverage you need may vary between insurance companies, and for many smaller operations a basic commercial property insurance policy is enough on its own.
Where commercial building insurance stops being enough is the point most owners find out the hard way — at claim time. The base form is written around physical damage to things you own at a stated location. It does not follow your income, it does not follow your data, and in California it does not follow water that arrives from outside the building.
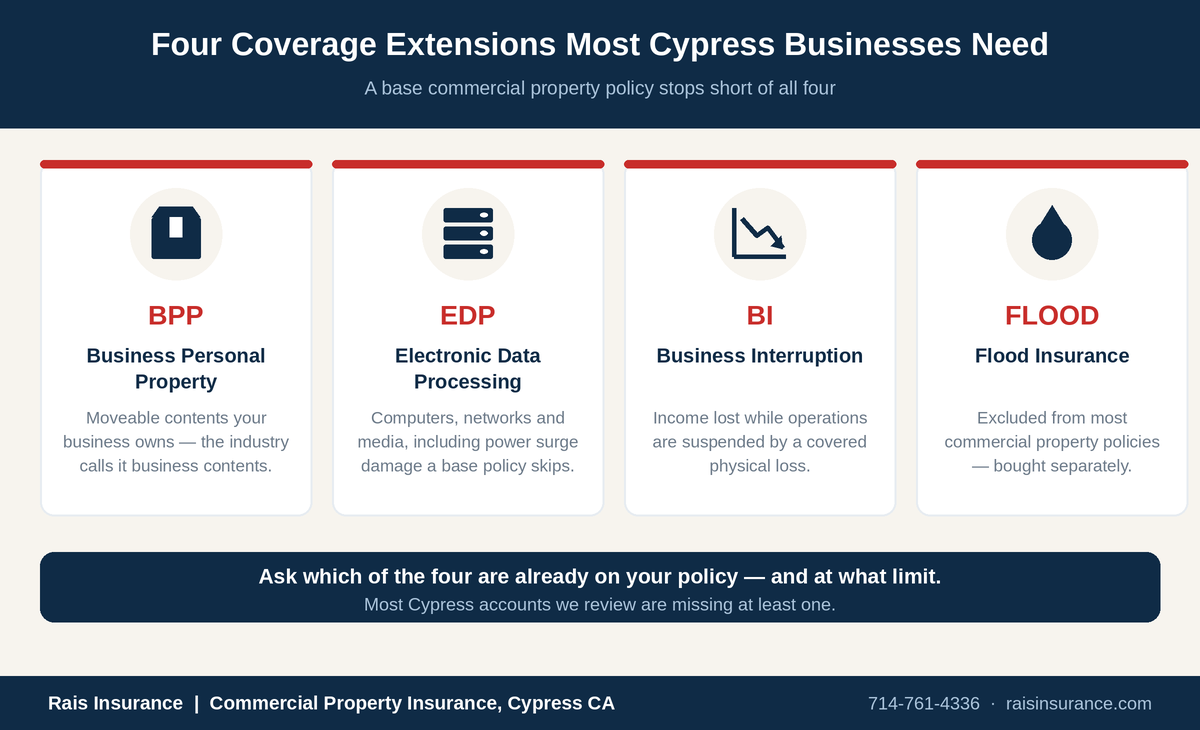
Four Commercial Building Insurance Extensions Cypress Businesses Need
Some of the most popular commercial building and property insurance extensions are:
Business Personal Property (BPP) Coverage
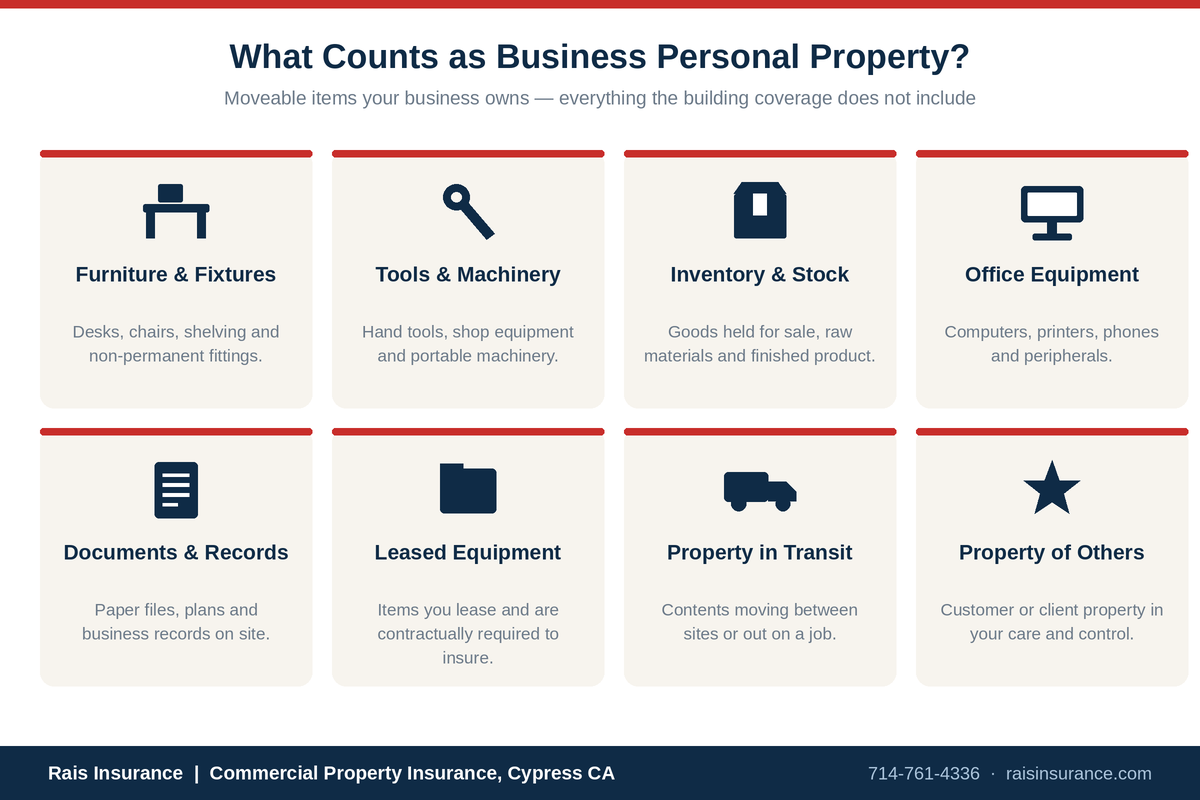
For your business to be protected, it’s imperative to keep track of the value and cost of your commercial property. The insurance industry refers to business personal property as “business contents”, a term for the moveable items owned by any business. In simple words, BPP is the extension of a commercial property policy that addresses those specific items. Though commercial building and property insurance covers a majority of business equipment, business personal property coverage is what reaches the smaller under-covered areas the building limit never touches.
In practice, BPP is where the following sit: furniture and fixtures, tools and machinery, inventory and stock, office equipment, paper records, leased equipment you are contractually required to insure, property in transit between sites, and customer property in your care. Keeping a current schedule of these against your commercial building insurance limits is the single most useful piece of housekeeping a Cypress business can do before renewal.
Electronic Data Processing (EDP) Insurance Coverage
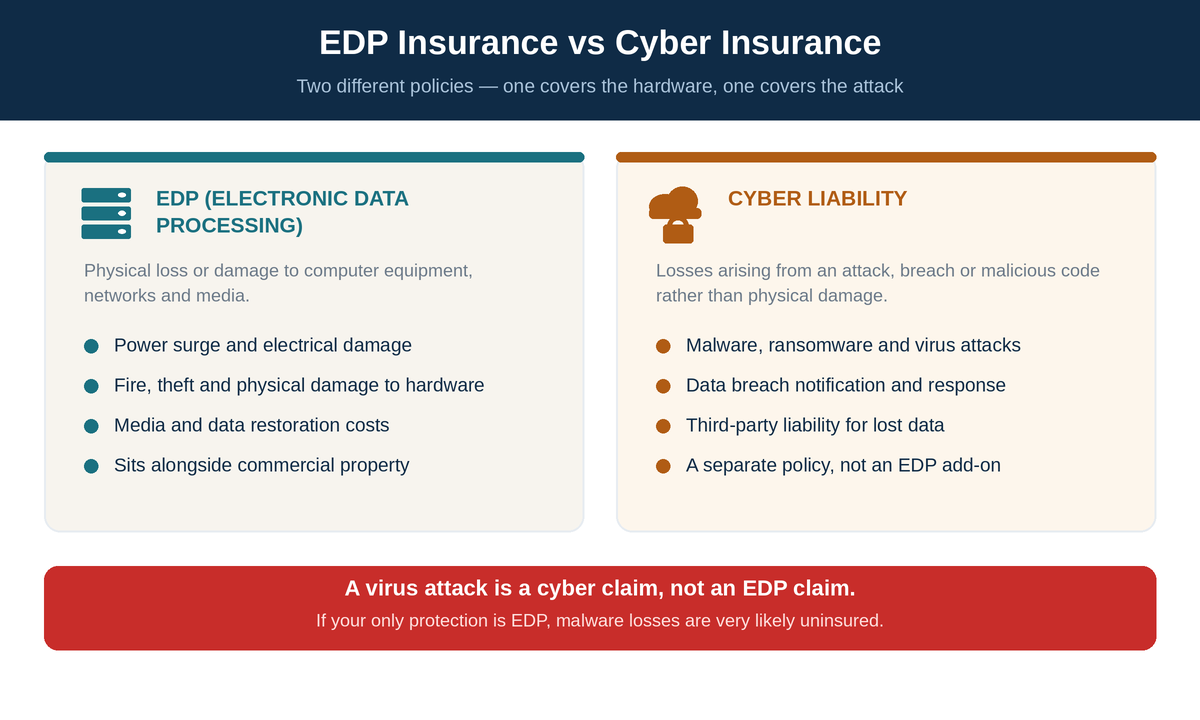
You can purchase this commercial property extension for your computer-related equipment. It is common for commercial property policies to cover fire damage but not to reach computer networks, and EDP includes causes such as power surges that a base form typically excludes.
Where EDP Ends and Cyber Insurance Begins
This is worth stating plainly, because it is the most common misunderstanding we correct on Cypress accounts: EDP is written around physical loss or damage to hardware, networks and media. A malware infection, a ransomware demand or a virus attack is a cyber liability claim, not an EDP claim. Wordings differ by carrier and some forms include limited data restoration, but if your only protection is an EDP endorsement, an attack is very likely uninsured.
The two policies sit alongside each other rather than replacing one another. EDP handles the surge that kills your server; cyber handles the ransomware that locks it. A technology-dependent business in Cypress generally needs both alongside its commercial building insurance, and we quote them separately so you can see what each one costs.
Business Interruption Insurance
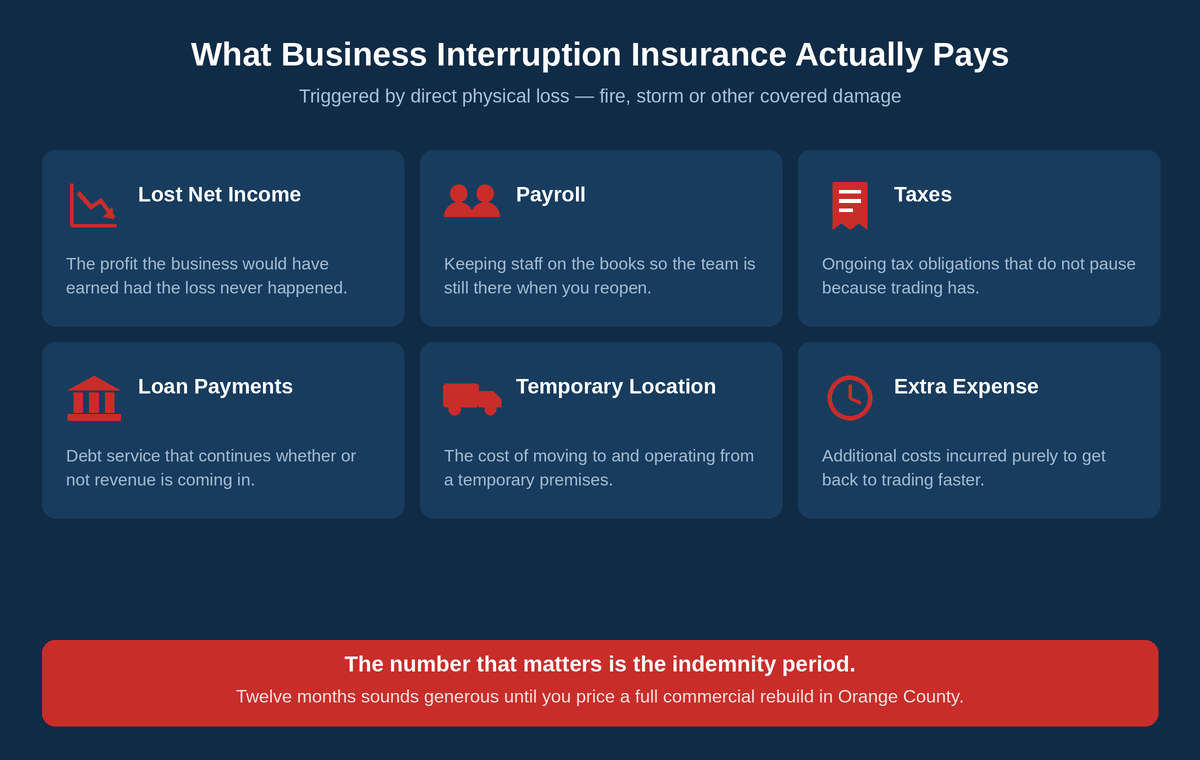
Business interruption insurance compensates lost income if a company’s operations are suspended due to direct physical loss, such as that caused by any natural calamity or fire. In addition to managing expenses, this insurance covers moving to a temporary location, taxes, loan payments and payroll. It is the coverage that keeps a business solvent through the months between the loss and reopening.
How Much Business Interruption Cover Do You Actually Need?
The limit matters less than the indemnity period — the number of months of lost income the policy will fund. Twelve months is the common default, and it sounds generous until you price a full commercial rebuild in Orange County: permits, contractor availability, materials and inspection routinely take longer than owners assume, and trading does not return to its old level on the day the doors reopen.
Two other details are worth checking on your own commercial building insurance wording. Payroll is sometimes limited to a shorter period than the main indemnity period, which can leave you funding staff yourself part-way through the closure. And extra expense — the money you spend purely to reopen faster — is not always included at a meaningful limit, even though it is often the cheapest part of the whole claim to fund and the fastest way to protect the customer base.
Flood Insurance
Flood is not covered by most commercial property insurance policies. To be protected from the subsequent harm, you’ll need to acquire separate coverage. Make sure you know what your property insurance policy actually does. If you are not sure, let us review your policy and we’ll help find a solution that fits your needs. Whether you need it comes down to the flood zone your Cypress premises sits in and what your lender requires — both of which we can check for you before you commit to anything.
Do You Need Commercial Property Insurance If You Work Remotely?
The page used to say every company needs commercial property insurance whether or not it has its own building. That is close to right, but worth being precise about: a fully remote business does not need building coverage, and buying it would be a waste. What it does need is business personal property and, almost always, electronic data processing.
The reason is that a homeowners policy will not cover property used to earn income. Laptops, servers, tools, stock held at home and business records are all excluded or severely sub-limited on a personal policy. For a remote Cypress business the right commercial building insurance structure is usually BPP plus EDP plus liability, with no building coverage at all — which is also considerably cheaper than the packaged policy a broker might reach for by default.
Cypress Businesses We Cover
We place commercial building insurance for professional and medical offices, light industrial and technology businesses along the Katella Avenue and Valley View corridors, warehouses and distribution units, retail units and restaurants, contractors and trades, and fully remote or hybrid businesses run from Cypress addresses. If you also carry business insurance on the operation itself, both can sit on one renewal date so nothing lapses between them.
How to Choose the Right Commercial Property Insurance Cypress?
At Rais Insurance, our insurance agents can assist you in determining what type of policy and coverage is appropriate for your business. As we assess how your business operates, we will offer you customized coverage options that are cost-effective to protect your business. No matter how large or small your claims are, we are there to assist you whenever you need our help or guidance.
If you would rather run the check yourself first, four questions get you most of the way: is business personal property scheduled at a current value, is EDP present or are the computers relying on the base form, what is the indemnity period on the business interruption section, and has flood been addressed or simply left excluded. Those four answers tell you more about a commercial building insurance policy than the premium does.
How to Get Your Cypress Commercial Property Insurance Quote
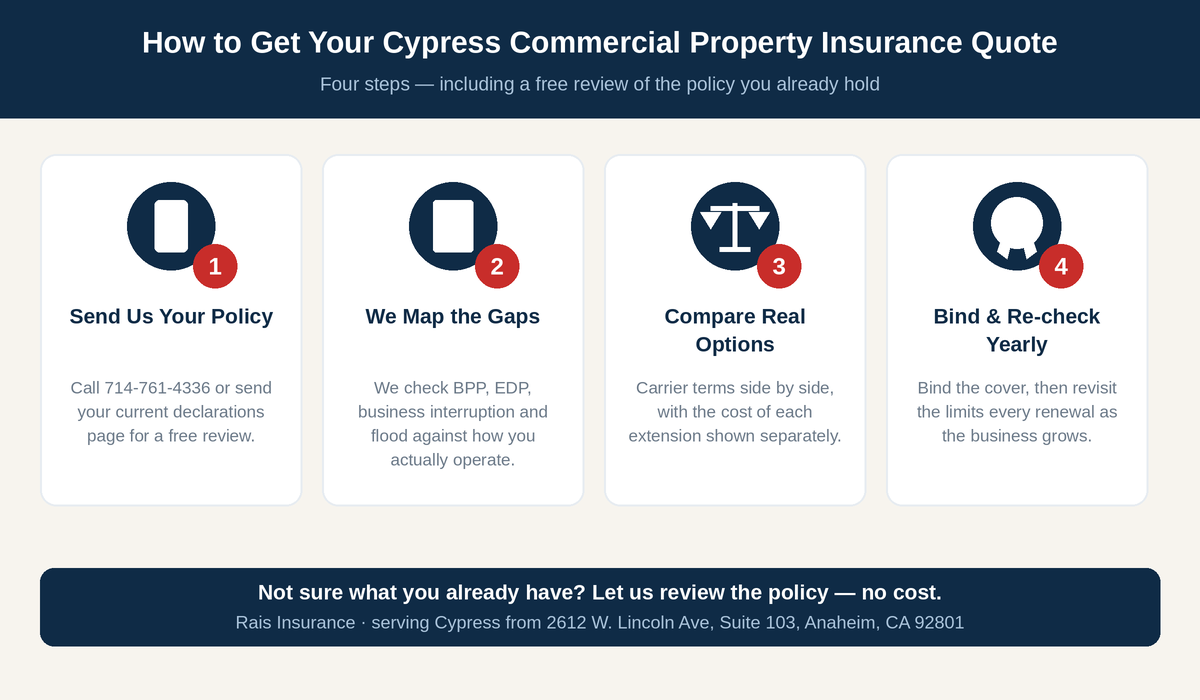
A quote for a Cypress commercial building insurance policy runs in four steps, and the policy review at the start costs nothing:
- Send us your current declarations page, or call 714-761-4336.
- We map the gaps — BPP, EDP, business interruption and flood — against how you actually operate.
- We compare carrier options and show the cost of each extension separately, not bundled into one figure.
- Bind the cover, then we revisit the limits every renewal as the business grows.
Frequently Asked Questions About Commercial Property Insurance in Cypress
What is business personal property (BPP) coverage?
Business personal property is the part of a commercial building insurance programme that covers what the industry calls business contents — the moveable items a business owns, as opposed to the building itself. It covers furniture and fixtures, tools and machinery, inventory and stock, office equipment, business records, leased equipment you are required to insure, and often property in transit or property of others in your care. BPP is the extension of a commercial property policy that addresses those specific items.
What does EDP insurance cover, and does it cover virus attacks?
Electronic data processing insurance covers computer-related equipment, networks and media, including causes a base commercial property policy typically does not reach, such as power surges. It is written around physical loss or damage to hardware and media. Malware, ransomware and virus attacks are generally handled by a separate cyber liability policy rather than by EDP, so do not assume an EDP endorsement protects you against an attack. Wordings vary by carrier, so the specific form should be checked.
Does commercial property insurance cover computers and servers?
Only partly. It is common for commercial building insurance policies to cover fire damage but not to reach computer networks in the way a technology-dependent business needs. Electronic data processing coverage is the extension written specifically for computer equipment, networks and media, which is why most Cypress businesses that depend on their systems add it rather than relying on the base policy.
What is business interruption insurance and how does it work?
Business interruption insurance compensates lost income when a company’s operations are suspended by direct physical loss, such as damage caused by fire or a natural calamity. Alongside lost net income it can cover payroll, taxes, loan payments and the cost of moving to and operating from a temporary location. It is triggered by covered physical damage, so it does not respond to a downturn or a loss of custom on its own.
How much business interruption coverage do I need?
The figure that matters is the indemnity period — how many months of lost income the policy will fund. It should reflect a realistic timeline for permits, contractors and rebuilding in Orange County plus the time it takes for trading to recover afterwards, not just the construction itself. Many policies default to twelve months, which is often short for a full commercial rebuild.
Do I need separate flood insurance for a business in Cypress, California?
Flood is not covered by most commercial property insurance policies, so protection has to be acquired separately through the National Flood Insurance Program or a private flood policy. Whether you need it depends on the flood zone your Cypress premises sits in and on your lender’s requirements. If you are not sure what your current policy does, Rais Insurance will review it at no cost.
Do I need commercial property insurance if my business is fully remote?
Usually yes, though not the building coverage. A remote business still owns laptops, servers, tools, inventory and records, and a homeowners policy will not cover business property used to earn income. What a remote Cypress business typically needs is business personal property and electronic data processing coverage rather than a policy built around a building.
What is the difference between building coverage and business personal property?
On a commercial building insurance policy, building coverage insures the structure and anything permanently attached to it — the roof, walls, wiring and installed fixtures. Business personal property insures what you could in principle carry out of it: furniture, equipment, tools, stock and records. A tenant who does not own the building usually needs business personal property only, while an owner-occupier needs both.
Does business interruption insurance cover payroll?
Yes. In addition to lost income, business interruption insurance can cover ongoing payroll, which is what allows a business to keep its team on the books during the closure rather than losing trained staff and rehiring after reopening. Payroll can sometimes be limited to a shorter period than the main indemnity period, so the wording is worth checking.
How do I get a commercial property insurance quote in Cypress?
Send your current declarations page to Rais Insurance or call 714-761-4336. We review what you already hold, check it against business personal property, electronic data processing, business interruption and flood, and come back with carrier options showing the cost of each extension separately. The review and the quote both cost nothing.